


5 Digital Transformation Challenges in Banking and How to Solve Them

September 3, 2026
- Legacy core systems and fragmented data remain the top blockers of digital transformation. Banks often underestimate their true infrastructure costs by 70–80%.
- Cybersecurity and compliance pressure are now inseparable. The average financial-sector data breach cost $5.56 million in 2025, and EU DORA enforcement is already in effect.
- Only 30% of banks succeed in their digital transformation strategies. Most failures trace back to governance and sequencing, not technology choice.
- A phased modernization roadmap consistently outperforms big-bang replacement programs.
Most banks planning digital transformation in banking already know the risks of standing still. What they underestimate is how intertwined the blockers are: a legacy core that won’t integrate cleanly, a compliance mandate that depends on data you can’t consolidate, and a board that wants ROI proof before committing to scale.
This guide is for CTOs, COOs, and Heads of Digital driving digital transformation in banking industry organizations. It pairs each of the core challenges of digital transformation in banking with a concrete fix and a step-by-step modernization roadmap.
What Is Digital Transformation in Banking?
Digital transformation in banking is the process of replacing manual, siloed, and legacy-dependent operations with integrated digital infrastructure. It spans core banking, customer onboarding, compliance reporting, and payments. It is a functional rebuild of how a bank operates — not a stack of disconnected digital projects.
The distinction matters. Many institutions launch digital initiatives while leaving their core architecture untouched. That is what produces the failed transformations McKinsey attributes to governance, not technology.
Only 30% of banks have succeeded in their digital transformation strategies. Most failures trace back to governance and sequencing.
By 2026, more than half the global population uses digital banking services, making baseline digitization table stakes. The real competition is now at the infrastructure level: who can launch, integrate, and scale faster.
5 Challenges of Digital Transformation in Banking with Direct Fixes
The table below maps each challenge to its most effective mitigation. Each section goes deeper into what the fix actually requires in practice.
| # | Challenge | Concrete Fix |
|---|---|---|
| 1 | Legacy core systems | Modular modernization via API-first middleware |
| 2 | Fragmented data and siloed operations | Unified data platform with real-time reconciliation |
| 3 | Cybersecurity and compliance pressure | Zero-trust architecture + compliance-by-design workflows |
| 4 | Cultural resistance to change | Structured change management with executive sponsorship |
| 5 | Budget constraints and ROI pressure | Phased pilot model with measurable milestones |
Challenge 1: Legacy Core Systems
Legacy infrastructure is the most persistent of the challenges of digital transformation in banking. Institutions may underestimate the true total cost of legacy systems by 70–80%. One mid-sized European bank estimated its core costs at €2 million annually. A full audit revealed the actual figure was €6.8 million — once compliance overhead, developer inefficiency, and downtime were counted.
Half of surveyed financial firms still rely on outdated or on-premises systems. And 57% are not monitoring threats in real time. Those gaps carry direct regulatory exposure: DORA has been in force across the EU since January 2025.
The fix: modular modernization. Teams add an API-first middleware layer that decouples customer-facing products from the underlying ledger. New capabilities — KYC flows, payment rails, open banking integrations — connect through standardized APIs. Core replacement is deferred until the risk is manageable. DashDevs used this approach when building Nexus, a platform for launching digital banks, and again when taking Dozens from concept to a licensed UK digital bank.
Industry benchmarks show that banks adopting a phased migration model typically reduce legacy operational costs by 30–40% while improving time-to-market for new features by up to 60% within 18 to 24 months.
| Tip | Why it matters |
|---|---|
| Audit every system touching your ledger before choosing a modernization vendor | Teams regularly find compliance reporting dependencies that aren’t documented anywhere |
Challenge 2: Data Silos and Fragmented Operations
Most traditional banks grew through product lines, regions, and acquisitions. Their data ended up in separate systems never designed to communicate. AML monitoring runs on one dataset. Customer onboarding on another. Risk scoring on a third. None of them reconcile cleanly.
This fragmentation creates two problems: poor customer experience and compliance failure. Both are expensive.
The fix: a unified data platform that aggregates customer and transaction data in real time. The key architectural decision is where the single source of truth lives and how every system writes to it. This is a fundamental infrastructure choice — not a reporting dashboard project.
AI use cases in banking built on fragmented data consistently underperform. About 70% of commercial banks have deployed AI in at least one core function. Effective personalization and fraud detection still require clean, unified data as the foundation.
Data silos don’t just slow operations. They make compliance reporting structurally unreliable — a different category of risk than a slow API.
Challenge 3: Cybersecurity and Compliance
This is the challenge that grew fastest. Financial-sector data breaches averaged $5.56 million per incident — 25% above the cross-industry average. Ransomware attacks on financial institutions increased 30% year-over-year. And 30% of breaches now involve a third-party vendor.
For traditional banks, cybersecurity challenges compound with every new integration. Cloud migrations expand the attack surface. Open banking APIs add external access points. Legacy systems running unpatched protocols raise breach risk further.
Compliance adds a second pressure track. DORA is enforceable across the EU, with penalties up to 2% of global turnover. US institutions face the SEC cyber disclosure rule mandating Form 8-K filing within four business days of a material incident.
The fix: zero-trust architecture, combined with compliance-by-design workflows. Zero-trust means every access request is verified regardless of source, with no implicit trust inside the perimeter. Compliance-by-design means audit trails and regulatory controls are embedded in the product layer from the start. Teams building custom fintech software from the ground up have a structural advantage here: they can architect compliance perimeters before operational complexity builds.
Challenge 4: Cultural Resistance and Organizational Friction
This is the digital banking challenge most guides acknowledge and few solve. Most digital transformations fail because middle management didn’t adopt the change, frontline staff reverted to old processes, and no one tracked behavioral change alongside technical delivery.
A bank deploys a digital onboarding flow, and digital adoption stays at 30%. The project is marked complete. Two years later, the branch process is still the primary route.
The fix: change management must be funded and measured as part of the transformation program. Concretely, that means:
- Naming a C-level sponsor who owns adoption metrics, not just delivery milestones
- Running parallel operations during transitions so staff can shift gradually
- Tying incentive structures to digital adoption, not just volume
For banks where the digital banking implementation strategy is already defined, the cultural layer is usually the gap between a plan that works on paper and one that works in practice.
Challenge 5: Budget Constraints and ROI Pressure
Investment cases for large-scale banking transformation are harder to make than they look. Technology budgets are rising, but so is board scrutiny. Institutions modernizing core architecture and scaling AI aim to improve their efficiency ratio by up to 15 percentage points through operational cost reduction, yet leadership still demands milestone-based ROI before committing to full-scale programs.
The complication: most transformation benefits are hard to isolate in the first 12 months. Cost reduction, reduced compliance exposure, and faster product velocity compound over time. This creates a stalling pattern where pilots never reach scale.
The fix: a phased model with defined revenue or cost milestones at each gate. The pilot proves the approach, and the milestones justify the next phase. The scale program runs on evidence.
Which Banking Processes to Digitize First
Not every process digitizes with the same return. In digital transformation in banking, four areas produce the clearest early wins across bank modernization projects:
| Process | Why start here |
|---|---|
| Customer onboarding and KYC | Manual KYC takes days and costs more per customer than automated flows; real-time identity verification cuts time and compliance overhead together |
| Core banking and ledger | Without clean, real-time transaction data, risk, compliance, and personalization built on top are compromised |
| Payments infrastructure | Real-time payments and banking APIs are baseline expectations; open banking payments in the UK grew ~70% year-over-year between 2024 and 2025 |
| Compliance reporting | Automated reporting reduces manual overhead and creates the audit trail DORA requires |
DashDevs applied the onboarding-first pattern in a digital identity automation engine for a Saudi banking institution. For ledger and core choices, see the core banking solutions teams are evaluating in 2026, and the open banking API guide for payment and data rails.
Teams that digitize compliance reporting early avoid retrofitting it under deadline pressure later.
A 5-Step Modernization Roadmap for Banks
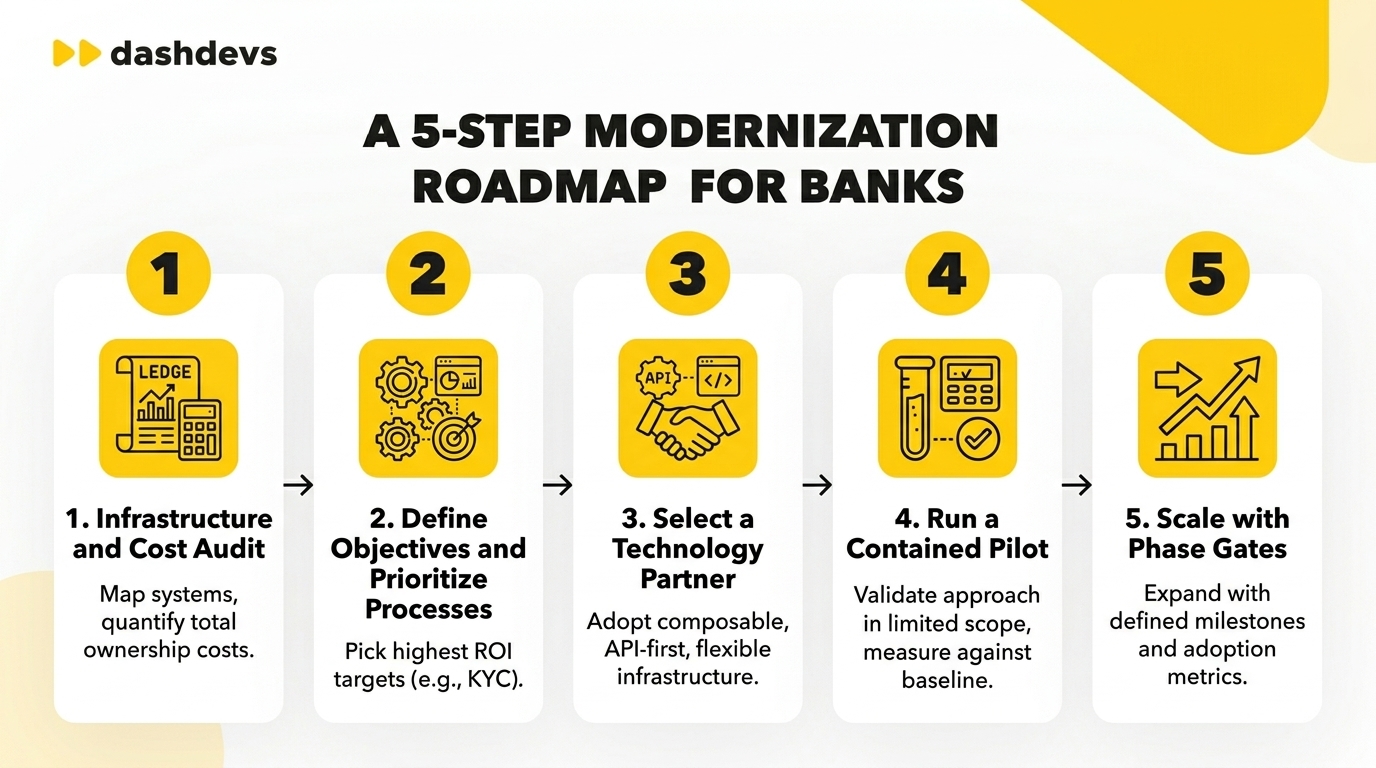
These challenges of digital transformation in banking are manageable when the program is sequenced correctly. Here is the approach that consistently works across bank modernization engagements:
Step 1: Infrastructure and cost audit
Map every system touching the ledger, payments, onboarding, and compliance reporting. Quantify the true total cost of ownership, including hidden overhead. This baseline becomes your ROI comparison point.
Step 2: Define objectives and prioritize processes
Pick the two or three processes with the highest cost-to-digitize ratio. KYC and compliance reporting almost always rank at the top. Set measurable targets: onboarding time, cost per application, compliance reporting hours.
Step 3: Select a technology partner
The build-vs-buy-vs-partner decision is where most programs stall — which is why early fintech consulting matters. Full custom builds are slow. Off-the-shelf products create vendor lock-in. A composable, API-first infrastructure with source-code access gives flexibility without starting from zero. See the digital banking solutions and modular platforms teams are evaluating now.
Step 4: Run a contained pilot
Validate your approach in one geography, product line, or customer segment. Measure against the Step 1 baseline. This is your evidence package for the scale decision.
Step 5: Scale with phase gates
Expand by process or region, with a defined milestone before each gate opens. Pair technical delivery with adoption metrics. Our podcast on Bank 5.0 and agentic banking covers how leading institutions are thinking about the next evolution.
Banking is moving from speed to trust as the competitive axis in embedded banking infrastructure. The institutions that close their digital gaps first are building a structural advantage, not just an operational one.
What to Digitize vs. What to Modernize: A Practical Split
Not every legacy process needs replacing. Some need wrapping via an API layer, and others need full re-architecture.
| Process | Approach | Why |
|---|---|---|
| Core ledger | Modular wrap or phased replacement | Full rip-and-replace risk is too high; API middleware extends life while new infrastructure builds |
| Customer onboarding / KYC | Full digitization | High manual cost, clear ROI, low dependency on legacy core |
| Compliance reporting | Automate a layer on top of existing data | Faster than rebuilding; DORA is current law, not a future deadline |
| Payments infrastructure | Modern API-first integration | Open banking rails and real-time payments require clean integration points |
| Branch operations | Augment, not replace | Customer preference for complex transactions still includes human touchpoints |
The Digital Onboarding Gap
One of the most measurable digital banking challenges is onboarding drop-off. Customers who can’t open an account in under five minutes on mobile are choosing digital-first alternatives. The global neobank market is projected to reach $322 billion in 2026. Its primary advantage is onboarding speed.
The pattern we see consistently: banks invest in a digital onboarding UI but leave back-end KYC and identity verification to manual processes. The front end looks digital; the actual process is not.
Full digitization of the onboarding-to-KYC pipeline typically cuts onboarding time from days to minutes. This is also where AI in finance delivers the clearest early return on investment.
Read how digital onboarding connects to daily banking processes in from digital onboarding to daily banking.
Benefits of Digital Transformation in Banking
The benefits banks gain from this transformation are well-documented. What changes at the operational level is worth being specific about.
| Benefit | What changes in practice |
|---|---|
| Faster product velocity | Modular architecture lets teams launch products without rebuilding from scratch |
| Lower compliance overhead | Automated reporting cuts manual hours and creates the audit trail regulators now expect in near real time |
| Improved fraud detection | AI-powered monitoring catches anomalies manual review misses; most institutions have already deployed AI fraud countermeasures |
| Reduced operational cost | Cloud migration and process automation consistently deliver 30–40% infrastructure cost reductions |
DashDevs took Tarabut Gateway from zero to MENA’s first regulated open banking platform in 9 months, integrating 8 banks and reaching 200K+ users — an example of what modular delivery can unlock when sequencing is right.
The goal of banking digital transformation is to rebuild the operational foundation so every channel runs on the same real-time data.
Building the Path Forward
The challenges of digital transformation in banking are real. They are also predictable. Every bank navigating this faces the same five friction points: legacy infrastructure, fragmented data, compliance pressure, cultural resistance, and budget constraints.
What separates successful digital transformation in banking programs is sequencing. Start with the processes where ROI is clearest. A well-run digital banking transformation builds outward from that foundation rather than trying to modernize everything at once. The neobank app development company model shows what is possible when you build the infrastructure correctly from the start. Traditional banks can reach a comparable outcome via a more constrained, phased path — and digital transformation services help keep that path executable.
Last updated: September 2026
Share article
