


Insurtech Trends 2026: What to Build First and What to Skip

October 16, 2026
- Insurtech is the application of digital technology to insurance operations, distribution, and risk assessment. In 2026, the 12 trends below vary sharply in implementation readiness: agentic AI and embedded insurance are deployable now.
- Your core system matters more than your trend list. Five of these 12 trends require an API-first policy administration system before they deliver real value. If you are still on a legacy PAC, start there.
- DashDevs delivered an insurance platform MVP in 3 months for Centinel, cutting risk-assessment time by 75% and making contract generation 4x faster.
- Embedded insurance adds the most near-term revenue for fintech distributors, with low implementation effort when the underwriting API is already available.
- AI governance is not optional for carriers in the EU and US. High-risk rules under the EU AI Act covering life and health insurance pricing took effect for most providers in August 2026.
Insurance technology has moved from a discussion topic to a delivery problem. Carriers know they need AI underwriting. Fintechs know embedded insurance is a margin opportunity. The real question in 2026 is which tech you can actually ship and in what order.
This article gives you 12 ranked technology trends in the insurance industry with a short implementation requirements block per trend, a prioritization matrix, and a segment map at the end. The insurtech trends covered range from deployable today (embedded insurance, claims automation) to the pilot stage (small language models, parametric smart contracts). Use it to decide which digital trends in the insurance industry are worth funding now and which still need their prerequisites in place.
What Is Insurtech and Why It Matters Now
Insurtech is the application of technology to design, distribute, and operate insurance products more efficiently and with better risk accuracy than traditional methods allow. How insurtech is reshaping insurance is clearest in two places: underwriting that took weeks now runs in minutes on a trained model, and coverage that required a broker now appears as a one-click offer at checkout. It covers the full value chain: distribution, underwriting, policy management, claims, and reinsurance.
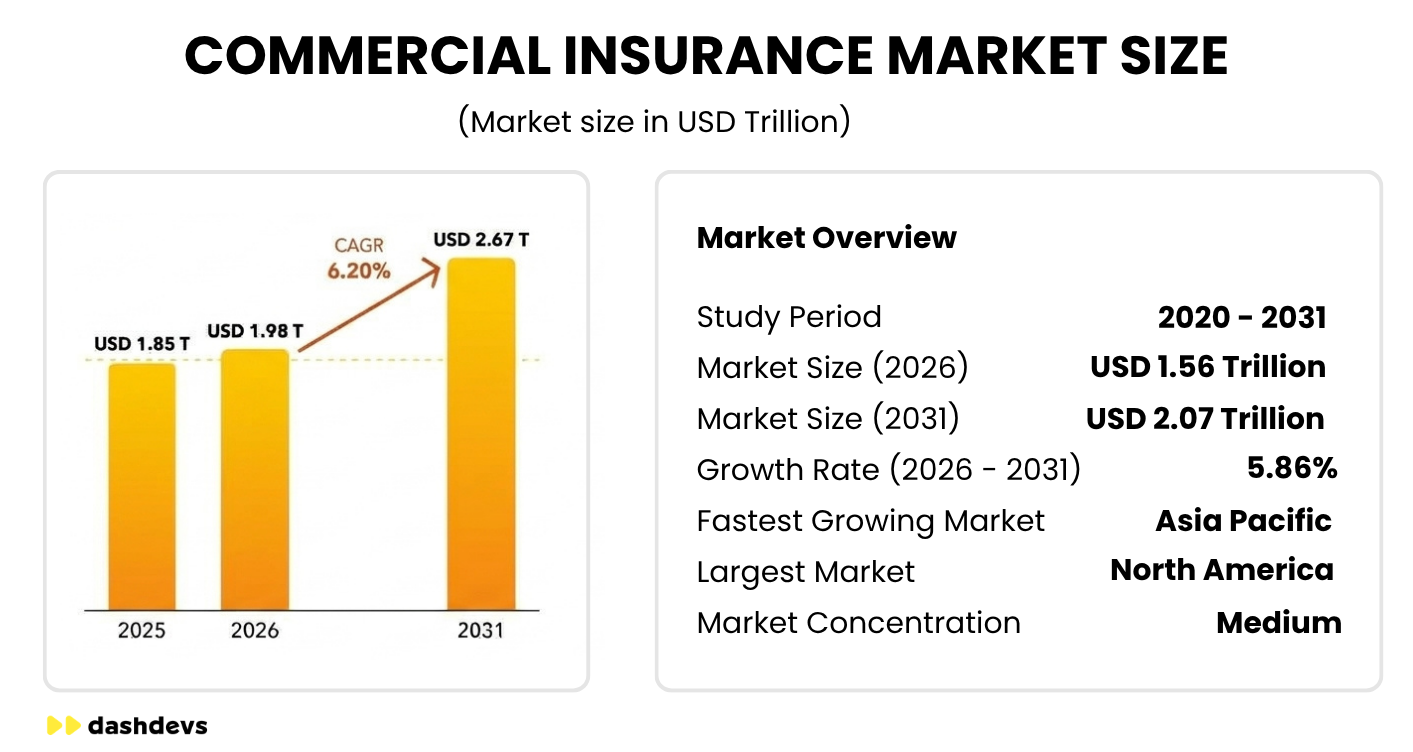
The global insurtech market was valued at approximately $7.5 billion in 2025, according to Mordor Intelligence’s 2025 Insurtech Market Report, and is expected to grow at a CAGR of around 37% through 2030. Growth is concentrated in AI-enabled underwriting platforms and embedded distribution channels, not in traditional broker digitization.
The implication: technology in the insurance industry is no longer incremental. The insurance trends that topped lists in 2022 are now baseline table stakes. The insurance industry technology trends that matter in 2026 are the ones that compound on a modernized data and integration foundation. Tracking trends in the insurance technology space without that foundation means investing in the right tools on the wrong base.
12 Technology Trends in the Insurance Industry 2026
The trends below are ranked by how quickly you can ship them and how much each one depends on having a modernized core system in place first.
1. Agentic AI in Insurance
Agentic AI refers to AI systems that pursue multi-step goals autonomously, using tools, APIs, and memory, without requiring human input at every decision point. In insurance, agents handle end-to-end workflows: gathering loss data, checking policy terms, routing claims, and generating draft settlements.
What it takes to implement: A structured data layer with clean policy, claims, and customer records. API access to policy administration and claims systems. A governance framework that defines which decisions the agent can make autonomously and which require human review. Pilot on a single, contained workflow before deploying broadly.
Who should prioritize it: Carriers with high claim volumes and structured internal data. MGAs running manual intake workflows.
2. Generative AI Copilots for Insurance Teams
Generative AI copilots assist underwriters, claims handlers, and agents in drafting, summarizing, and comparing documents. They reduce the time spent on routine document work and improve consistency across policy wording. A McKinsey 2025 Global Insurance Report found that AI in insurance applications focused on document generation and summarization showed the fastest adoption curve of any GenAI use case in financial services. The fintech AI development patterns for these builds transfer directly to insurance.
What it takes to implement: A fine-tuned or retrieval-augmented model trained on your policy library and claims history. Integration with your document management system. Output review protocols before Copilot suggestions are committed to live documents.
Who should prioritize it: Any insurer with large underwriting or claims teams dealing with high document volume. The ROI is fastest in commercial lines where policy customization is frequent.
Start with a copilot that summarizes incoming claims documents, not one that generates policy wording. Summarization has a much lower error cost and builds team trust in the tool before you expand its scope.
3. Predictive Analytics and Automated Underwriting
Predictive analytics lets insurers assess risk at the individual and portfolio levels using structured and unstructured data. Automated underwriting applies those models to accept, reject, or price applications without human intervention for standard cases. This is one of the most proven insurance technology trends: the technology is mature, and the data requirements are well understood.
On the Centinel insurance platform, DashDevs built an automated underwriting module that reduced risk-assessment time by 75% and cut contract generation from hours to minutes. The MVP was live in three months. The key was connecting the model to structured historical claims data early in the build, not retrofitting it later.
What it takes to implement: Clean historical claims and loss data (minimum three years for most lines). A model monitoring process to catch drift. Regulatory sign-off on automated decision logic in markets with explainability requirements.
Who should prioritize it: Carriers in personal lines and small commercial. MGAs with high application volume and a repeatable risk profile.
4. Claims Automation and RPA
Robotic process automation handles repetitive, rule-based tasks in claims: intake, document classification, reserve setting, payment triggering, and status updates. Combined with AI, it handles a broader range of cases with less rule maintenance. According to Deloitte’s 2025 Insurance Outlook, a carrier that has deployed end-to-end RPA in insurance claims processing, reports a 30–50% reduction in average handling time for standard claims.
What it takes to implement: Process documentation for the workflows you want to automate. Integration with your claims management system. Exception handling rules for edge cases the bot cannot process. Review the RPA in the insurance claims processing guide for a detailed breakdown of the integration layer.
Who should prioritize it: Any carrier or TPA with claims volume above 500 cases per month. The economics are clear, and the technology is proven.
The bottleneck in most claims operations is not the adjusters. It is the hand-offs between systems. Once you automate the routing and document handling, your adjusters can focus on the judgment calls that actually require them.
5. Embedded Insurance from the Distributor Side
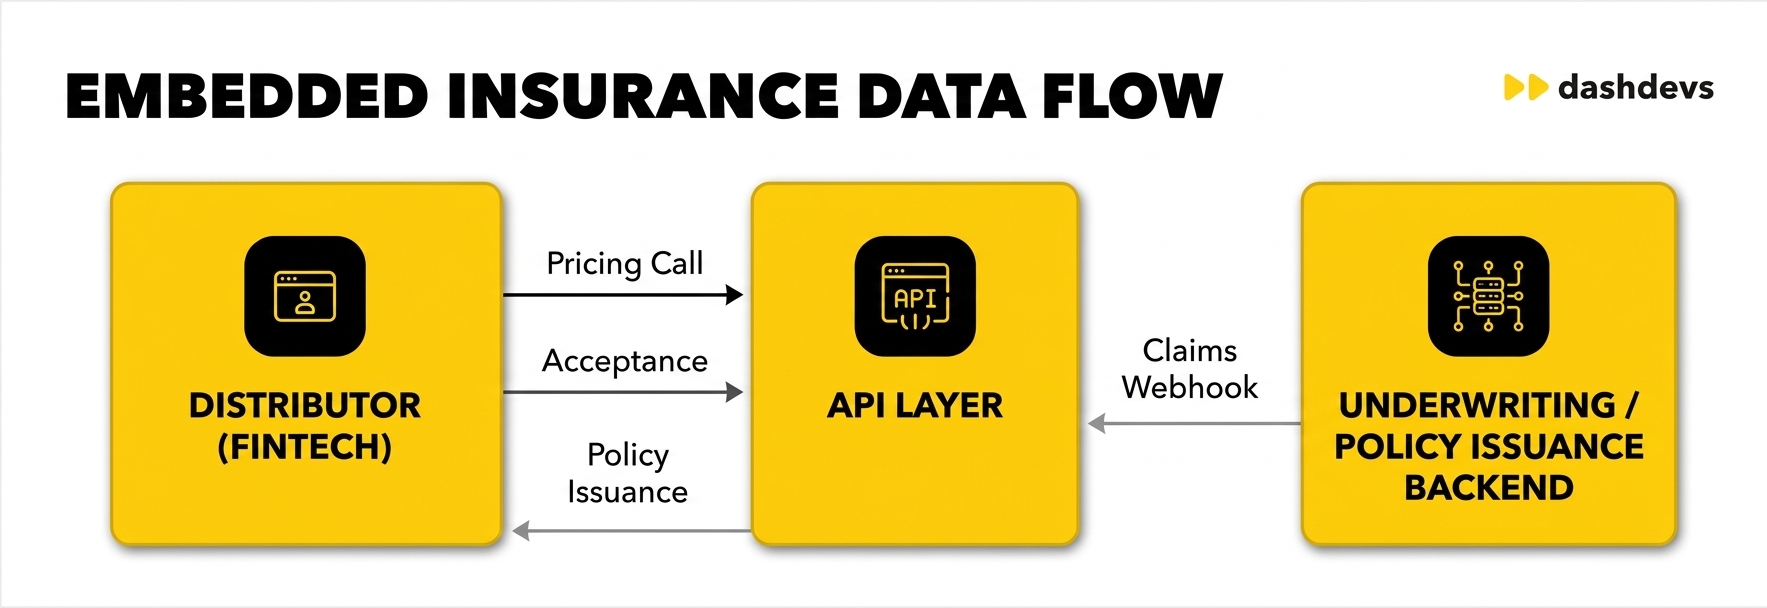
Embedded insurance is the integration of insurance coverage into a non-insurance product or transaction at the point of sale. For fintechs and banks, this means connecting to an underwriting API and offering coverage at checkout without sending the customer to a separate insurance journey.
This is where competitors’ coverage stops. Most articles on embedded insurance describe the insurer’s architecture. Here is what it looks like from the distributor side:
- Insurance API at checkout: The distributor calls a pricing and eligibility API at the point of purchase. The customer sees a pre-filled offer with one-click acceptance. Policy issuance happens in the background.
- Policy and claims data flows: The distributor needs a webhook or API subscription to receive policy status updates and claims outcomes. This data feeds customer support and refund logic.
- KYC reuse: If the distributor already has KYC data on the customer, the insurer’s API should accept it directly. This avoids re-verification and is now standard in most embedded insurance API specifications. The fintech API integration patterns we use across 70+ provider integrations apply directly to insurance API connections.
We covered the structural difference between embedded and traditional distribution of financial products in detail. The insurance version follows the same pattern with one additional layer: claims data must flow back to the distributor to close the customer experience loop.
What it takes to implement: An underwriting partner with a documented API. Integration into your checkout or onboarding flow. Legal review of disclosure requirements in your markets. The fintech integration layer is often the fastest path.
Who should prioritize it: Fintechs, neobanks, and e-commerce platforms with existing customer flows. Time to value is the shortest of any trend on this list when the insurance API partner is already chosen.
6. IoT, Telematics, and Usage-Based Insurance
Usage-based insurance (UBI) prices coverage based on actual behavior rather than demographic proxies. Telematics in auto, wearables in health, and smart home sensors in property all feed the same mechanism: real-time data that makes risk assessment more accurate. The advantages of big data analytics in this context are well-documented: insurers that price on behavior rather than cohort reduce adverse selection measurably.
What it takes to implement: A data ingestion pipeline for device telemetry. A model that translates behavioral signals into premium adjustments. Customer consent and privacy compliance, especially under GDPR and state-level US data laws. A mobile or web interface where customers can see their data and understand how it affects pricing.
Who should prioritize it: Auto insurers, health insurers with wellness programs, and property insurers in high-risk geographies. Moving from dashboards to predictive insights is the right framing for the analytics build here.
7. Parametric Insurance and Smart Contracts
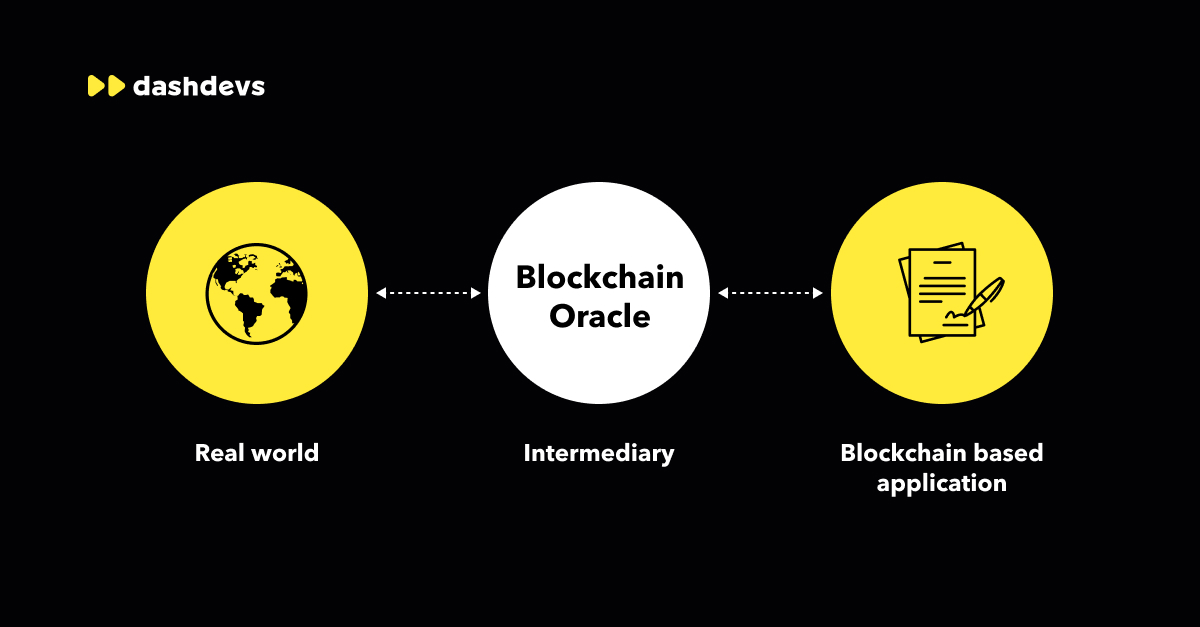
Parametric insurance pays a fixed amount when a predefined trigger event occurs, such as rainfall below a threshold or wind speed above a limit, without requiring a traditional loss assessment. Smart contracts in fintech execute payment automatically when the trigger condition is verified on-chain.
The combination is powerful for agriculture, travel, and catastrophe coverage. The technology is mature enough for pilots but still requires careful oracle selection and legal review in most jurisdictions.
What it takes to implement: A reliable, auditable data oracle for the trigger event. Smart contract development and audit. Legal framework review: parametric products are regulated differently from indemnity products in most markets. Reinsurance capacity that understands parametric structures.
Who should prioritize it: Specialty insurers, MGA-built products for emerging market risks, and carriers exploring climate-related coverage lines. Pilot in a single geography before scaling.
8. Core Systems Modernization: API-First and Cloud-Native
This is the foundational trend that determines whether the other 11 work. An API-first policy administration system exposes all core functions as callable endpoints. A cloud-native architecture scales horizontally and deploys without downtime. Five of the other trends on this list require this layer to be in place before they deliver real value: agentic AI, embedded insurance, automated underwriting, claims automation, and IoT data ingestion.
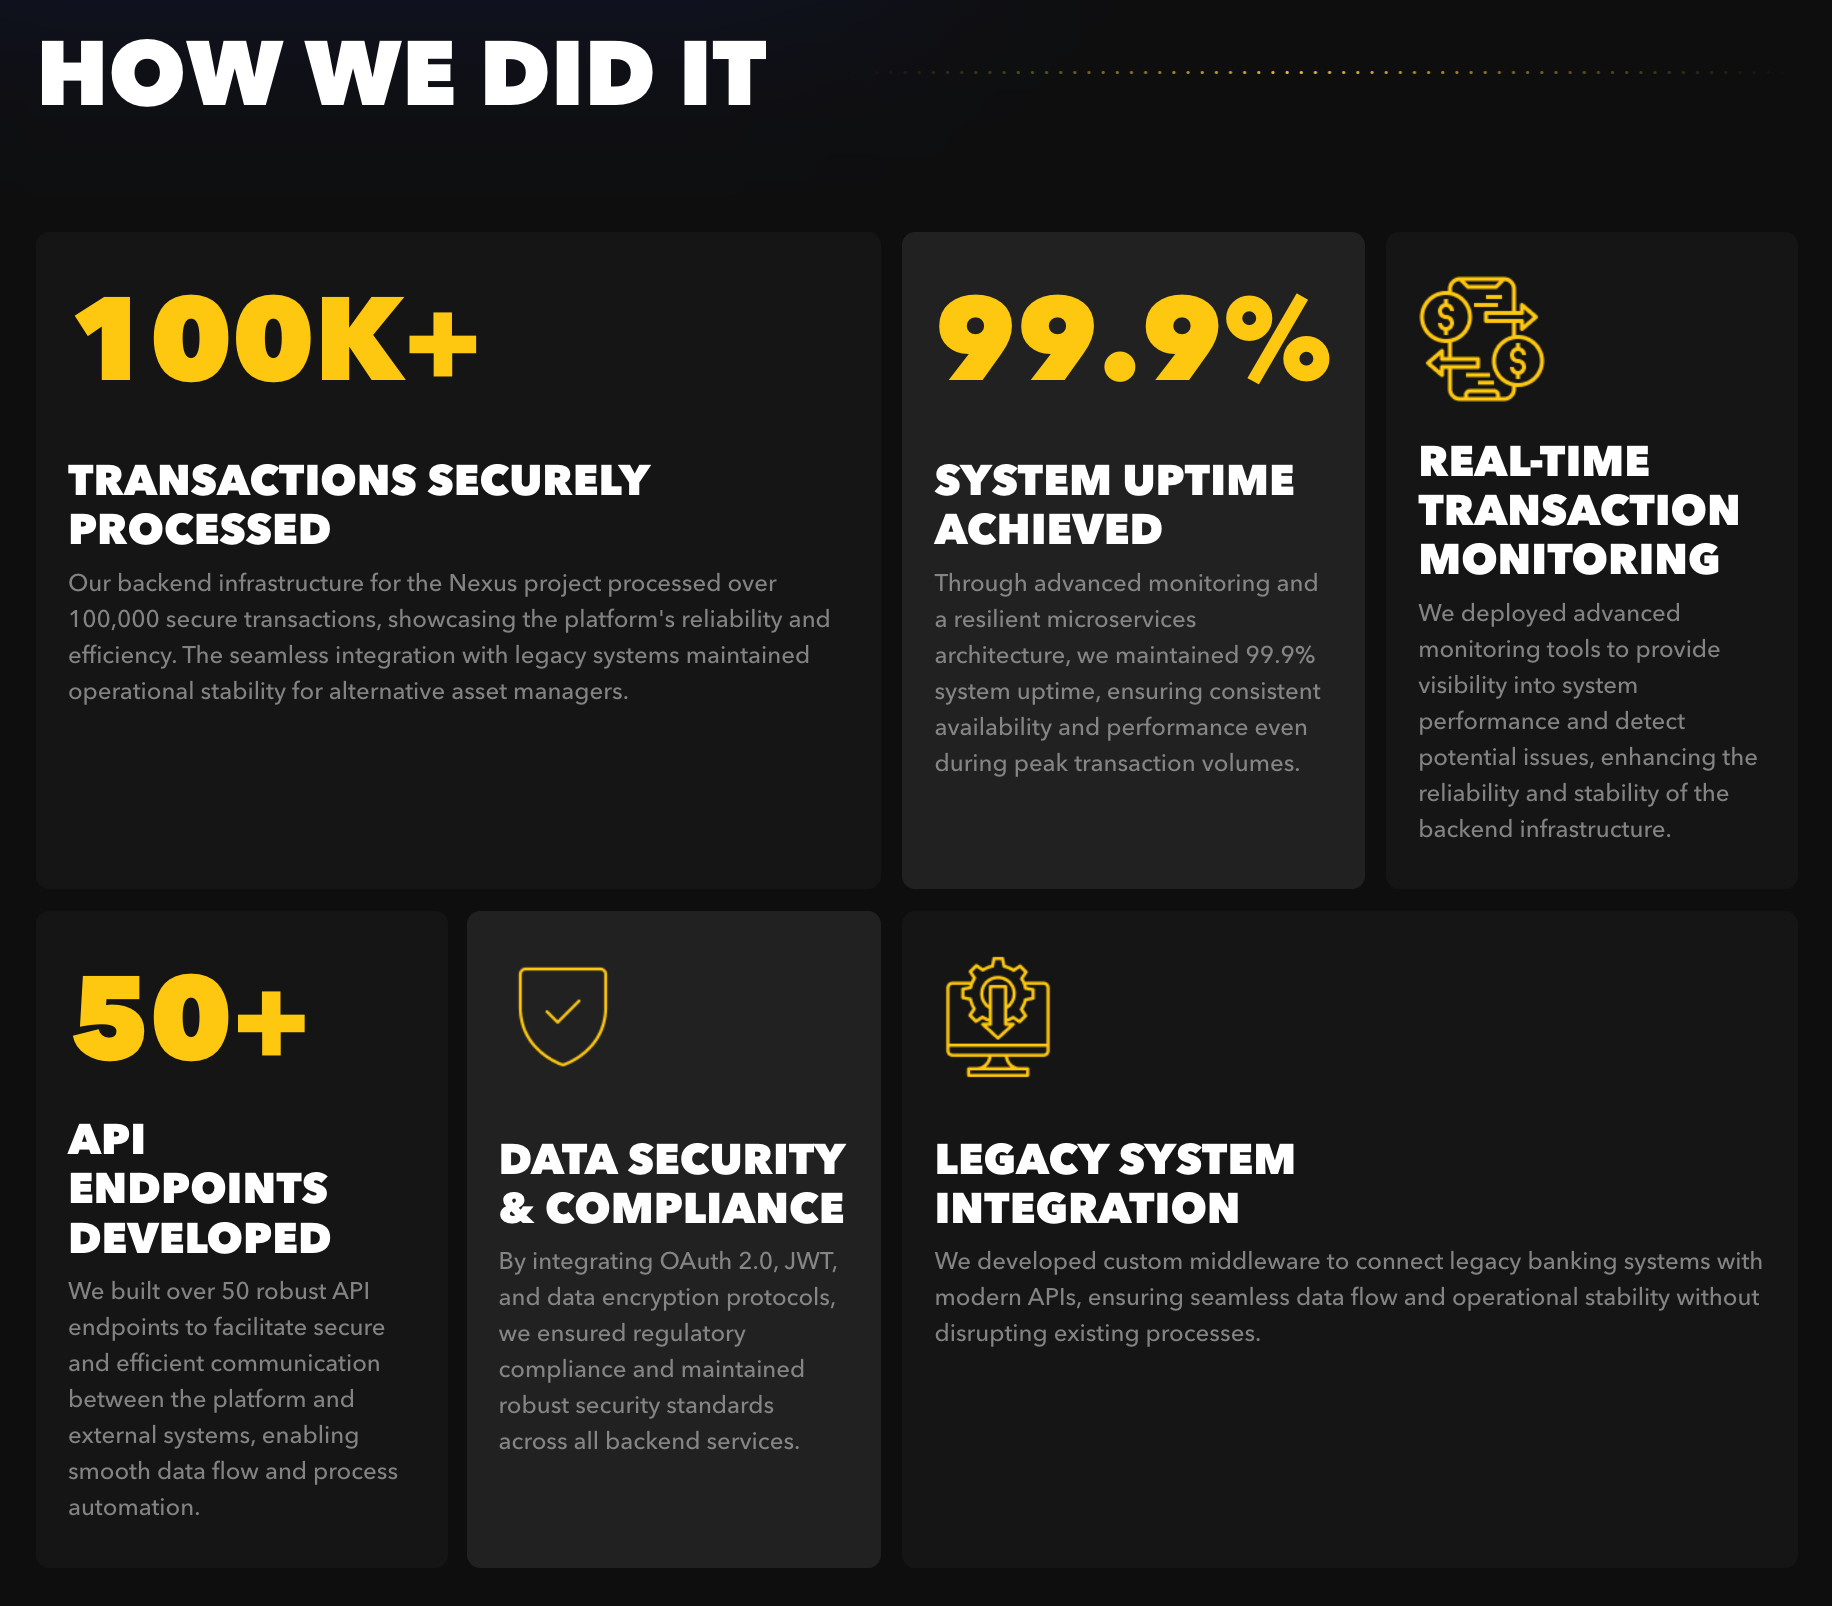
The Nexus case study shows how DashDevs connected legacy systems to cloud infrastructure, creating the integration layer that made downstream digitization possible. The pattern is the same in insurance: you do not replace the legacy system on day one; you wrap it with APIs and migrate functionality incrementally.
What it takes to implement: An architecture assessment to identify which core functions need API exposure first. An integration layer (middleware or API gateway) that sits between legacy and new systems. A phased migration plan. Digital transformation services scoped to your specific core system.
Who should prioritize it: Any carrier or MGA still running a monolithic policy administration system. This is the prerequisite, not a trend to defer.
9. Small Language Models for Insurance Operations
Small language models (SLMs) are compact, domain-specific AI models that run on-premises or in a private cloud. They handle classification, extraction, and generation tasks on sensitive insurance data without sending that data to a third-party API. For carriers with strict data residency requirements, SLMs are the practical alternative to large public models.
What it takes to implement: A labeled dataset from your own documents for fine-tuning. Infrastructure for on-premises or private cloud inference. Evaluation benchmarks specific to your use cases. This is a 2026 trend to pilot rather than scale immediately: the tooling is improving quickly.
Who should prioritize it: Carriers and reinsurers in jurisdictions with strict data localization rules (EU, certain MENA markets). Also relevant for any insurer handling medical or sensitive personal data.
10. Cyber Risk and Cyber Insurance
Cyber insurance is growing because cyber risk is growing. According to IBM’s Cost of a Data Breach Report 2026, the average cost of a significant cyber incident for a financial services firm reached $6.29 million in 2026. Insurers are responding with tighter underwriting criteria, higher premiums, and new product structures that cover operational technology and supply chain exposure.
For carriers writing cyber, the underwriting challenge is data quality: many applicants cannot provide the security posture information that accurate pricing requires. Automated cyber risk assessment tools that scan public-facing infrastructure are beginning to close that gap.
What it takes to implement: For carriers: a cyber underwriting model that connects to external threat intelligence data. For fintechs distributing cyber coverage: an API integration with an underwriting partner that handles the risk assessment automatically. Risk management technology in financial services covers the assessment frameworks that apply here.
Who should prioritize it: Carriers are expanding into SME and mid-market commercial lines. Any fintech distributing to business customers.
11. AI Governance and Compliance Automation
AI governance in insurance means having documented, auditable processes for how AI models are trained, validated, monitored, and updated, especially for models that make or inform underwriting and claims decisions.
Regulatory status as of October 2026: The EU AI Act classifies AI systems used in life and health insurance pricing and risk assessment as high-risk under Annex III. Obligations for high-risk system providers, including conformity assessments and ongoing monitoring, apply from August 2026 for most providers (source: EU AI Act, Article 6 and Annex III, published in the Official Journal of the EU, 2024). In the US, the NAIC AI Model Bulletin (adopted 2023, updated 2025) requires insurers to maintain accountability frameworks for all AI-driven insurance decisions, including the ability to explain individual outcomes. Source: NAIC, Model Bulletin on the Use of Artificial Intelligence Systems by Insurers, 2025 revision.
What it takes to implement: Model documentation (training data, feature importance, validation results). A monitoring pipeline that flags distribution shift. An audit trail for automated decisions that is accessible to regulators and customers. Integration with your compliance team’s review process before any AI model goes into production in underwriting or claims.
Who should prioritize it: All carriers and MGAs using AI in underwriting or claims in the EU and US. This is not optional.
12. Insurtech Partnerships and Ecosystem Integration
Carriers that cannot build every capability in-house are partnering with specialist insurtechs for specific functions: embedded distribution, parametric products, cyber underwriting data, AI-powered FNOL. The partnership model reduces time to market and allows each party to focus on their structural advantage. With 15+ years in regulated fintech and 70+ fintech providers integrated across client projects, DashDevs has direct experience with what makes these integrations work: a clear API contract, defined data ownership, and a governance process for incidents.
What it takes to implement: Vendor due diligence with a focus on data security and API stability. Legal frameworks covering data sharing and liability. A technical integration layer that does not create a single point of failure. The custom fintech software development approach we use for these builds is documented separately.
Who should prioritize it: Carriers and MGAs that want to move faster than their internal development capacity allows. Also relevant for fintechs that want to offer insurance without building underwriting capability themselves.
Trend Prioritization Matrix
| Trend | Business Impact | Dependency on Core Modernization | Time to Value | Who Should Prioritize |
|---|---|---|---|---|
| Agentic AI | High | High | 6–12 months | Carriers, MGAs with high volume |
| GenAI Copilots | Medium-High | Low | 3–6 months | Any insurer with large document teams |
| Predictive Analytics / Automated Underwriting | High | High | 4–9 months | Personal lines carriers, high-volume MGAs |
| Claims Automation / RPA | High | Medium | 2–5 months | Carriers, TPAs above 500 claims/month |
| Embedded Insurance | High | Low | 1–3 months | Fintechs, neobanks, e-commerce |
| IoT / Telematics / UBI | Medium | Medium | 6–12 months | Auto, health, property insurers |
| Parametric / Smart Contracts | Medium | Low | 9–18 months | Specialty insurers, MGA pilots |
| Core Systems Modernization | High (Foundational) | N/A (is the dependency) | 12–24 months | All carriers on legacy PAC systems |
| Small Language Models | Medium | Medium | 12–18 months | EU/MENA carriers, sensitive data handlers |
| Cyber Insurance | High | Low | 3–6 months | Commercial lines carriers, fintech distributors |
| AI Governance | High (Compliance) | Low | 3–6 months | All carriers/MGAs using AI in EU or US |
| Insurtech Partnerships | Medium | Low | 1–4 months | Carriers and fintechs with capacity constraints |
Segment-to-Trend Map
Carrier on a legacy policy administration system: Start with core systems modernization. Without an API layer, agentic AI, automated underwriting, and embedded distribution cannot connect to your data. Run claims automation and GenAI copilots in parallel because they tolerate legacy environments better than the others.
MGA building a new digital product: Prioritize automated underwriting and GenAI copilots. Your lean team needs force multipliers on the underwriting and document workflows. Add claims automation at launch, then build toward IoT data ingestion as your book matures.
Fintech or bank adding embedded insurance: Embedded insurance is your fastest revenue path. Connect to an underwriting API, integrate the checkout flow, and set up the KYC data pass-through. Add AI governance documentation from the start so you are not retrofitting compliance later.
Specialty insurer exploring new risk lines: Parametric insurance and cyber risk are your growth levers. Both require specialist data partnerships rather than internal builds. Insurtech partnerships are the right vehicle. AI governance is mandatory before you put any model in front of regulators.
Share article
