


How Much Does It Cost to Build a Fintech App?

October 9, 2026
- Fintech app development cost is the year-one budget a founder sets to design, build, and scope compliance for a regulated product and app type.
- Choose the build path before the feature list. Custom, white-label, and composable infrastructure are different products, not different price tags for the same one.
- Compliance is a recurring operating cost. KYC and AML are the largest part of it after launch.
- Fintech Core, DashDevs’ composable fintech infrastructure and orchestration platform, is typically operational in 12 weeks.
- Plan year-two operations in the same raise as the build. Hosting, per-check KYC, AML, the annual audit, and the next release do not stop at launch.
You’re building a fintech product, and someone (an investor, a board member, or your co-founder) is asking what it costs. The honest answer is: it depends on decisions you probably haven’t made yet. The build path and compliance scope will each move the number more than any feature on your roadmap.
This guide prices those decisions directly for fintech founders, CTOs, and heads of product preparing a first raise or a Series A. Not hourly rates by geography. The actual cost drivers, with numbers from 100+ financial products DashDevs has delivered, including Dozens, a UK challenger bank, live in nine months.
Fintech App Development Cost: The Ranges That Actually Matter
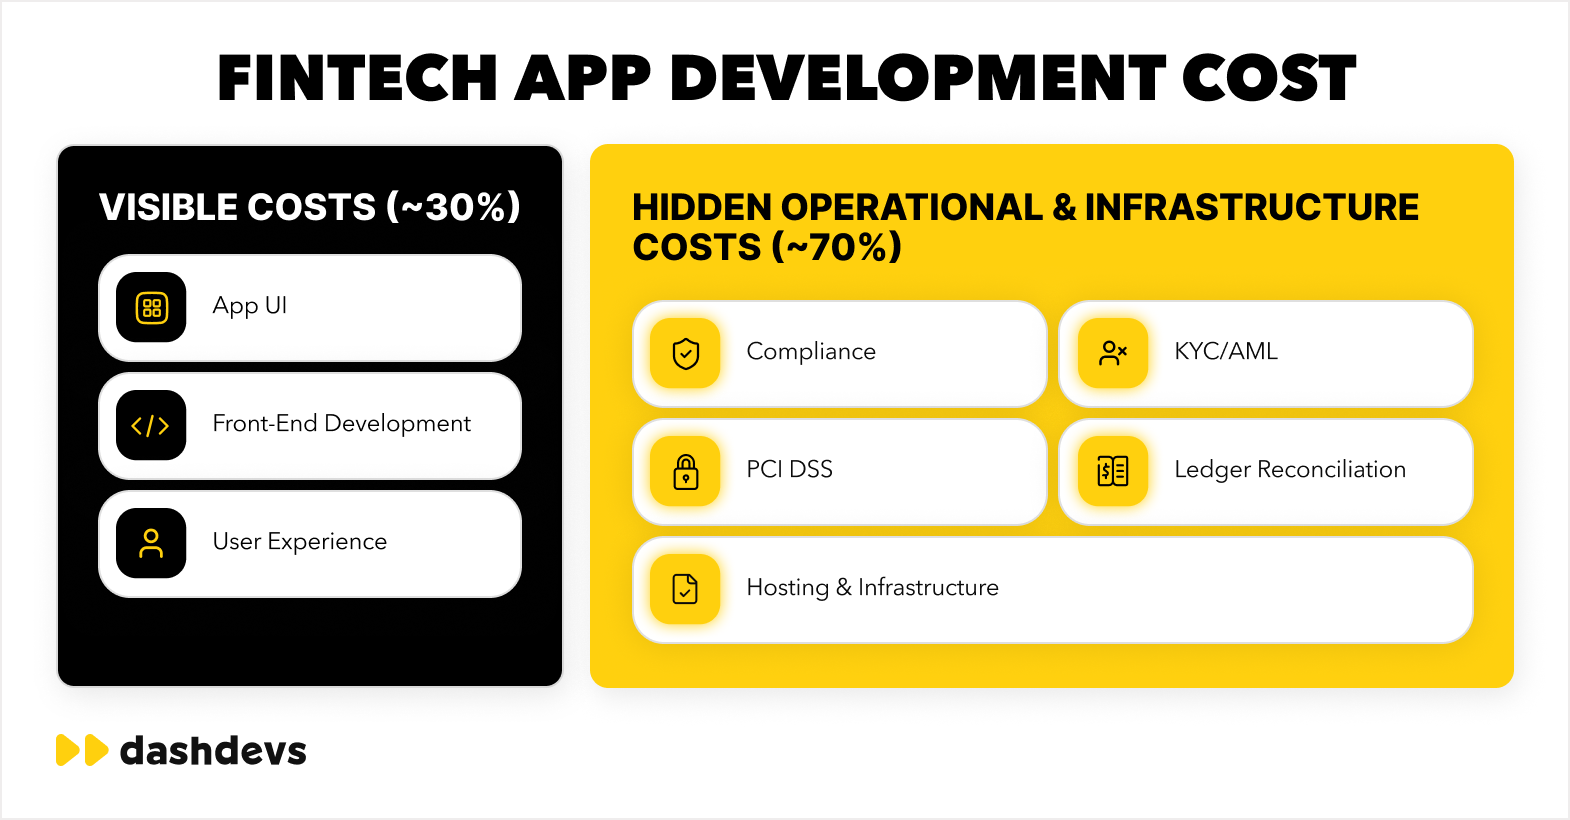
A fintech app development cost starts at around $150,000 for a lean payment or wallet MVP and reaches $800,000 or beyond for a fully licensed neobank or multi-market lending product. The range is wide because the category is wide. A consumer spending tracker and a regulated EMI launching in three markets have almost nothing in common technically.
The global fintech market was valued at $460.76 billion in 2026 by Fortune Business Insights, projected to reach $1.76 trillion by 2034 at an 18.2% CAGR. That growth creates real pressure on founders to launch faster than competitors. Build path decisions are exactly where that pressure shows up in your budget.
The table below gives you a starting point by product type. Ranges reflect DashDevs delivery data across 100+ financial products.
| App Type | MVP Range | Full Product Range | Typical Timeline |
|---|---|---|---|
| Neobank / digital bank | $300K – $500K | $600K – $1.2M+ | 9–18 months |
| Wallet/payments | $150K – $300K | $350K – $700K | 6–12 months |
| Lending / BNPL | $200K – $400K | $500K – $900K | 9–15 months |
| Investment/wealthtech | $200K – $350K | $450K – $800K | 9–14 months |
| Crypto-fiat/stablecoin | $250K – $500K | $600K – $1M+ | 9–18 months |
These ranges assume a single primary market. Add 25–40% for multi-jurisdiction compliance from launch.
For a detailed breakdown of banking-specific costs, see our banking app development cost guide.
Build Path Changes the Cost More Than Features
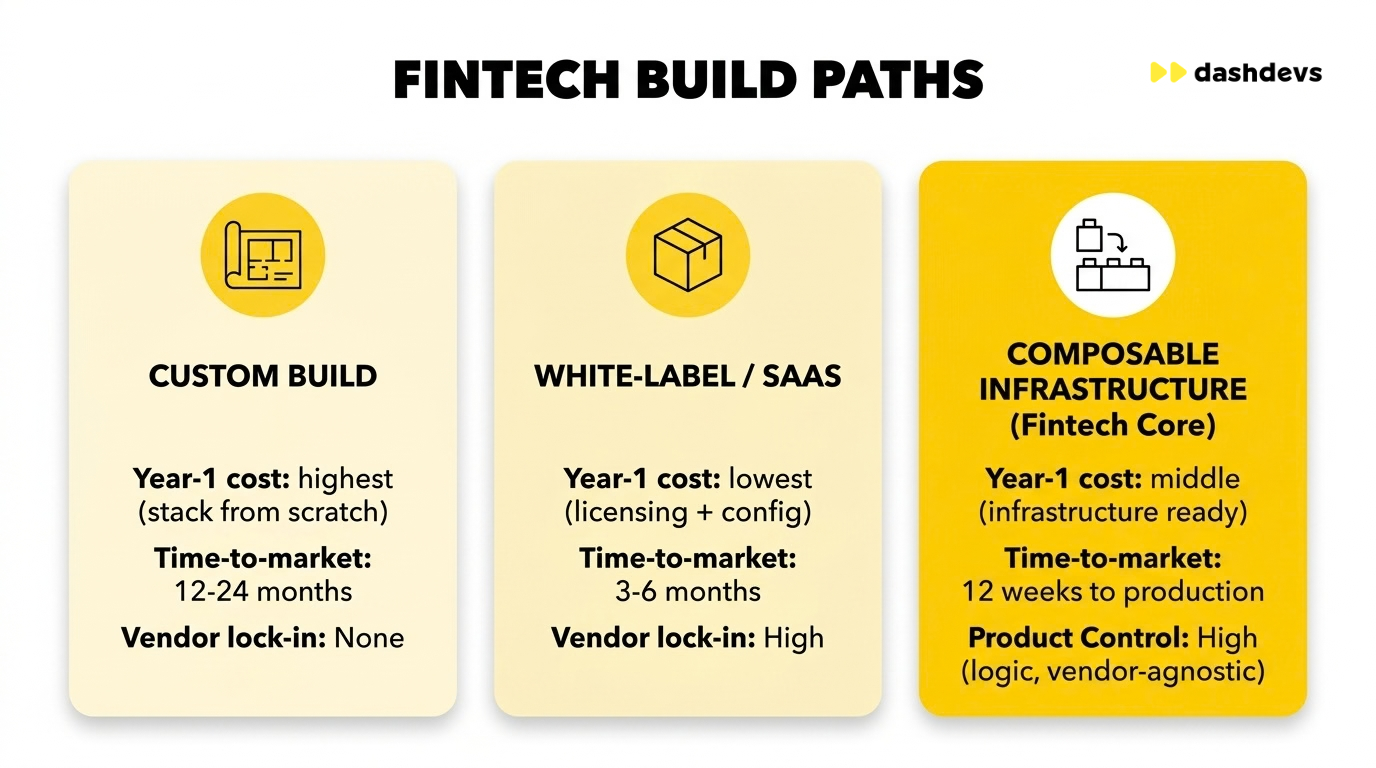
The single biggest cost decision in fintech isn’t what features you build. It’s whether you build the compliance infrastructure yourself, use a white-label platform, or take a composable infrastructure approach that sits between the two.
Most cost breakdowns compare regions and hourly rates. That analysis is useful for a staffing decision. It doesn’t help you understand why two products with identical feature lists can cost $200,000 or $800,000.
The table below shows how the three paths compare on what actually drives your budget.
| Custom Build | White-Label / SaaS | Composable Infrastructure (*Fintech Core) | |
|---|---|---|---|
| Year-1 cost profile | Highest: full stack from scratch | Lowest: licensing + config | Middle: infrastructure ready, product layer customized |
| Time to market | 12–24 months | 3–6 months | Typically 12 weeks to production |
| Product control | Full | Very limited | High: owns logic, vendor-agnostic |
| Vendor lock-in | None | High | Low |
| Compliance ownership | Yours to build and maintain | Provider’s, passed on to you | Yours, with infrastructure support |
| Best for | Licensed institutions with unique IP requirements | Concept validation, limited regulatory scope | Startups launching regulated products, EMIs adding products, institutions modernizing |
*Fintech Core is DashDevs’ composable fintech infrastructure and orchestration platform for launching, expanding, or modernizing regulated financial products.
It gives teams a faster starting point than a custom build, with more flexibility and control than traditional white-label or SaaS platforms. Fintech Core is typically operational in 12 weeks, includes 16+ modules, and provides access to 20+ pre-integrated vendor connections across KYC, card issuing, payments, and compliance monitoring.
For the full decision framework, read our article on a framework for build, buy, or partner decisions.
Compliance and Integration Line Items
Across the 100+ financial products DashDevs has delivered, compliance infrastructure (KYC, AML, PCI DSS, ledger, and payment integrations) typically accounts for a substantial share of the year-one build budget. The exact proportion varies by product type and regulatory scope, which is why it gets its own line-item table below rather than a single percentage. Most estimates skip it entirely or fold it into a footnote. That’s where budgets break.
Fenergo’s Financial Crime Industry Trends 2025 report found that average annual spend on AML/KYC operations now stands at $72.9 million per firm (Fenergo, 2025). For fintech startups building from scratch, that absolute figure is irrelevant, but the proportion it represents matters. You’re building compliance infrastructure for the first time with no existing processes to inherit, which means every dollar goes further at established institutions than it does at your stage.
The table below shows each major compliance line item, what it costs to set up, and what you pay every year after.
| Line Item | One-Off Setup Cost | Annual / Recurring Cost | Notes |
|---|---|---|---|
| KYC / identity verification | $15K – $40K | $0.50 – $3.50 per verification | Depends on provider tier and volume; |
| AML / transaction monitoring | $20K – $50K | $10K – $60K/year | Rules engine + ongoing tuning; mandatory for EMIs, neobanks, crypto. |
| PCI DSS scoping + audit | $15K – $35K | $8K – $25K/year | SAQ vs. a full QSA audit depends on the card data handling scope. |
| Ledger/reconciliation | $20K – $60K | $5K – $20K/year | Custom ledger is significantly more expensive; off-the-shelf adds integration cost. |
| Payment provider integrations | $10K – $30K per integration | $500 – $5K/month per provider | Open banking rails add regulatory overhead in the EU (PSD2, Status as of October 2026: active) and the UK (OBIE). |
| Open banking/data aggregation | $15K – $40K | $5K – $30K/year | Cost depends on number of bank connections and data refresh frequency |
On Fintech Garden, the fintech podcast by DashDevs, Igor Tomych made the case that teams who treat compliance as a design constraint rather than a post-launch checklist ship faster and spend less. A compliance architecture decision at week two costs hours to change. The same decision at week sixteen costs months.
For guidance on provider selection, see how to choose a KYC provider.
How Development Stage Affects the Fintech App Development Cost
The cost to develop fintech app products shifts significantly depending on what you’re building toward: a concept test, a market-entry MVP, or a fully scaled product. Each stage has a different scope and a different risk profile. The return on investment looks completely different too.
Prototype
A prototype is your cheapest validation tool. It gives you a working interface to test assumptions with real users before committing budget to full development. Most fintech prototypes cost 10,000–40,000 and take two to four weeks. They don’t include backend infrastructure, compliance, or integrations. The value is in proving the concept, not shipping a product.
Use a prototype when you’re still validating whether your core user journey works. Use it before raising a seed round if you need something tangible to show investors.
Proof of Concept
A proof of concept (PoC) tests a specific technical assumption in a real environment: one integration, one architecture pattern, or one regulatory approach. Cost ranges from $20,000 to $80,000. It takes two to eight weeks, depending on complexity.
PoCs are most useful for:
- Testing a specific payment provider integration before committing to it across your product
- Validating that a compliance architecture handles your transaction volumes at expected cost
- Confirming that your tech stack supports the data residency requirements of your target market
A PoC that catches a wrong technical assumption at week four is worth far more than the $30,000 it cost.
Minimum Viable Product
An MVP is your first production-ready release. It has enough features to get your first real users and gather real feedback. That’s also what demonstrates traction to investors. In fintech, an MVP must include all mandatory compliance components. You cannot ship a regulated product without them, even at an early stage.
Fintech MVPs cost between $80,000 and $300,000 depending on product type. A payment wallet MVP sits at the lower end of that range. A lending product or neobank MVP sits at the higher end. The timeline is typically 3–9 months.
The goal of an MVP is one thing: get real users using a real product. Every feature beyond that goal extends your timeline and your budget without reducing your risk.
Full Product
A fully featured fintech product is built for scale. It includes the complete feature set for your primary market, full compliance infrastructure, and the integrations your operations team needs to run the product without manual workarounds. This is what you’re building toward in your Series A or B funding cycle.
Cost ranges from $200,000 to over $1M depending on app type, as detailed in the table above. The timeline is typically 9–24 months from MVP, not from zero.
One thing that surprises most founders: the jump from MVP to full product is rarely a linear cost increase. The architectural decisions you made at the MVP stage either compound your costs at scale or contain them. That’s the hidden cost of technical debt in fintech.
For the technical context behind these architectural decisions, read our fintech architecture guide.
Cost of Building a Fintech App by Type
The cost ranges below are by product type and reflect DashDevs delivery data. Each section calls out the specific line items that consistently surprise teams at estimate time.
Neobank
A neobank at MVP level needs a current account with card issuance and a KYC/AML layer. Add a basic ledger and mobile clients, and that’s your MVP scope. That puts you at $300K-$500K. The full product adds investment features and savings products. A spending intelligence layer pushes it into $600K-$1.2M territory.
Neobanking is among the fastest-growing segments in fintech. Mordor Intelligence projects the global neobank market to reach $13.67 trillion by 2031, growing at a 10.82% CAGR from 2026. That competitive pressure is exactly why time-to-market matters as much as it does in the cost conversation.
Dozens, a UK challenger bank built with DashDevs, launched in nine months with a custom core banking platform, dual FCA licensing (eMoney + MiFID II), and 20+ vendor integrations. They acquired 25,000 users in the first year and secured £35M in funding. Based on DashDevs’ delivery analysis, the custom core proved 40% more cost-competitive than the white-label alternatives scoped during the initial build decision.
From the very early days, I was struck by DashDevs’ pragmatic approach of balancing development and business needs. It’s really rare to find a company that not only does tech for the sake of tech but also makes grounded decisions, taking into account business considerations. We built together a pretty complicated platform with 40 vendors in less than 18 months," — Aritra Chakravarty, CEO and Founder, Dozens
The nine-month figure refers to the initial MVP launch; the 18-month figure covers the full platform, including all 40 vendor integrations.
Wallet and Payments
A payment or wallet MVP is the most accessible entry point in fintech. Lean products with one payment rail and basic KYC sit at $150K-$300K. Multi-currency wallets with open banking integrations or cross-border rails move into $350K–$700K.
The cost to develop fintech app products in the payments category depends heavily on how many payment corridors you’re opening and how many PSPs you’re integrating. Each corridor requires its own compliance sign-off and integration work. Each integration adds 10K–30K in setup. For a detailed technical breakdown, read our digital wallet app development guide.
Lending and BNPL
Credit products carry hidden cost drivers. The decisioning engine and regulatory reporting layer are the two that consistently surprise teams at estimate time. A basic consumer lending MVP sits at $200k-$400k. BNPL with merchant integration and installment management adds significant backend complexity, pushing the range toward $500K-$900K.
Centinel, an insurance-adjacent credit product, reached MVP in three months under tight budget constraints. Their key decision: one credit product, one market, one KYC provider. That constraint kept the project inside budget. The lesson is that scope discipline in lending products delivers more cost control than any rate negotiation with a dev team.
For a breakdown of what PCI DSS audit scope means for card-handling products, read our overview of PCI DSS requirements.
Investment and Wealthtech
Investment products require MiFID II or SEC registration in most markets. Add a regulated custodian relationship and real-time market data feeds on top of that. Cost ranges sit at 200k-350k for MVP and 450k-800k for a full wealth management platform. The compliance and licensing overhead is the most significant cost differentiator from other fintech categories.
For benchmarks specific to trading platforms, see our cost to develop a stock trading app article.
Crypto-Fiat
Crypto-fiat infrastructure combines blockchain integration with regulated payment rails. That means two compliance frameworks, two sets of vendor integrations, and typically a travel rule solution. Budget 250K–500K for MVP and 600K–1M+ for a production-grade platform.
Tarabut, MENA’s first regulated open banking platform, built its core product on a $500K budget. The constraint drove a clear architectural decision: use best-in-class vendor integrations for compliance rather than build internal tooling. That decision reduced time-to-market and kept the budget predictable.
What Does Fintech App Development Cost in Year Two?
Year two spend is hosting, KYC volume, AML, the annual PCI DSS audit, penetration testing, maintenance, and the next release. Most cost estimates stop at launch. That’s where the real costs begin. Year two total cost of ownership typically runs 40–60% of the year one build budget.
The table below shows where that money goes for a mid-complexity licensed product.
| Cost Category | Typical Annual Range | Notes |
|---|---|---|
| Cloud hosting/infrastructure | $18K – $80K | Scales with transaction volume and data residency requirements. |
| KYC verifications (per-unit) | $0.50 – $3.50 × volume | High-growth products see this become the largest single line item by year two. |
| AML monitoring | $10K – $60K | Increases with transaction volume and geographic scope. |
| PCI DSS annual audit | $8K – $25K | Required annually for card-handling products. |
| Penetration testing | $10K – $30K | Annually; some regulators require semi-annual testing. |
| Maintenance and bug fixes | 15–20% of build cost | Industry standard; higher for products with complex integrations. |
| Feature development | $100K – $300K | Depends on the roadmap; rarely zero in year two. |
A product with a $400K year-one build cost and $200K in year-two operating costs has a two-year TCO of $600K. Very few founding teams model this in their initial raise. The ones that do are the ones who don’t run out of runway before reaching their next milestone.
The per-unit KYC cost is the line item that catches teams off guard most often. At low volumes, $1.50 per verification is immaterial. At 50,000 new users per month, it’s $75,000 per month in operating costs. Plan for growth in your compliance budget as well as your infrastructure budget. Both scale with users.
DORA (Digital Operational Resilience Act) entered full application in January 2025 and adds annual resilience testing and incident reporting obligations for fintech firms operating in the EU. Status as of October 2026: active. Budget $15,000-$40,000 for initial DORA compliance work and $8,000-$20,000 annually for ongoing testing requirements.
Igor Tomych, CEO at DashDevs, puts it this way:
The teams that get caught off guard by year-two costs are the ones who budgeted for features and forgot to budget for operations. In fintech, compliance doesn’t go away after launch. It scales with you. Budget for it like infrastructure, not like a one-time project cost.
For a broader view of how to approach fintech outsourcing and cost optimization across the delivery lifecycle, read our guide on fintech software outsourcing.
Which Build Path Fits Your Situation
Different stages and regulatory positions call for different approaches. Here’s how to match your situation to the right option.
- Pre-seed founder validating a payments concept: Your app development cost at this stage should be minimal. Use white-label or SaaS to validate user demand. Total cost: 50k-150k. Don’t build compliance infrastructure yet. Prove the product first, then raise it to build it properly.
- Seed-stage startup launching a licensed EMI or wallet: Composable infrastructure reduces time-to-market by 30% and lets you own the product layer without rebuilding compliance plumbing. Budget $200K-$500K for year one. If you want to know more, check out our article on launch-ready fintech infrastructure.
- Series A fintech adding a new product line: If you have an existing licensed entity, adding a product with Fintech Core is significantly faster than a full custom build. Modules are pre-integrated. Budget 100k-300k for the new product.
- Licensed institution building a greenfield digital product: Custom build or composable infrastructure, depending on whether vendor agnosticism matters more than time to market. Budget $500K-$1.2M+, 12–24 months.
- Crypto-fiat or stablecoin infrastructure provider: Plan for dual compliance frameworks and travel rule integration on top of your standard multi-market licensing. Budget $600K-$1M+ for a production-grade platform.
For a broader view of how to structure your fintech engagement, explore fintech integration services.
The most common mistake at this decision point is choosing the path that optimizes for the current stage rather than the next one. A white-label product that validates your concept is valuable. A white-label product that you then have to rebuild from scratch 18 months later because the platform can’t support your compliance requirements costs twice as much as building on composable infrastructure from the start.
Know your 18-month goal before you choose your build path. That’s the number that determines which option is actually cheaper.
Share article
