


Hire Dedicated Fintech Developers: 2026 Cost & Vetting Guide

October 23, 2026
- The right hire is a team that has shipped regulated financial products, not a team that can learn fintech on your timeline.
- Dedicated team, in-house, staff augmentation, and freelancers differ on speed, cost, control, and who owns compliance when something fails.
- PCI DSS scope, KYC/AML flows, double-entry ledgers, and idempotent payment APIs are the competencies a standard technical interview misses.
- The visible monthly rate is not the cost. The first six months of a dedicated fintech developer typically run 1.3–1.6 times that rate.
- A dedicated team on Fintech Core by DashDevs is typically 12 weeks into production, compared with eight to twelve months building the same foundation from scratch.
The right answer on hiring a specific fintech team model depends on one thing: whether the team you hire has actually shipped regulated financial products before. This guide gives you the model comparison, vetting scorecard, and real cost breakdown. It is written for CTOs and founders at Series A to C fintechs, licensed banks adding product lines, and seed-stage teams deciding whether to build in-house or partner out.
Which Hiring Model Fits Your Situation?
Most decisions about where to find fintech developers for hire come down to four variables: speed, cost, control, and who owns compliance when something goes wrong. The table below maps each model to those variables and to the specific situation where it wins.
| Model | Cost structure | Ramp-up | Compliance ownership | Best fit |
|---|---|---|---|---|
| Dedicated team | Monthly retainer, fixed scope | 4–6 weeks | Vendor accountable, client oversight | Series A+ fintechs, regulated products, multi-year builds |
| In-house hiring | Salary + benefits + overhead | 3–6 months per senior hire | Client owns everything | Large FIs with existing fintech teams and compliance infrastructure |
| Fintech staff augmentation | Per-resource day rate | 2–3 weeks | Shared, client-led | Teams with a strong internal PM who need specific skills fast |
| Freelancers | Per-project or hourly | Days to weeks | Client owns everything | Short-term tasks with no compliance surface |
Segment-to-option map:
- EMI launching in the EU: A dedicated fintech team is the only model that bundles PCI DSS knowledge, KYC/AML flows, and vendor integrations into a single accountable unit.
- Licensed bank adding a card product: Outsourcing vs team augmentation can work if you have an internal lead who can own compliance. Otherwise, a dedicated team removes the coordination risk.
- Seed-stage MVP: Freelancers or a small dedicated team can get a proof of concept to market. Migrate to a full dedicated team before you touch regulated payment rails.
- Series B scaling a payments platform: A dedicated development team with embedded compliance competence becomes a long-term competitive asset.
If you need to go deeper on the outsourcing side of this decision, see how the models compare in our guide to fintech software outsourcing.
For context on how fintech hiring decisions are shifting in 2026, see the episode on fintech hiring trends on Fintech Garden, the fintech podcast by DashDevs.
What Does “Fintech-Ready” Actually Mean?
Fintech-ready is a set of production experiences most developers outside regulated finance have never had. The gap matters most when you hire fintech app developers for a consumer-facing product.
A senior backend engineer who has shipped e-commerce at scale isn’t automatically qualified to build a payment system. The problems in fintech are different: double-entry ledgers that must reconcile to zero under any failure condition, idempotent payment APIs that handle duplicate requests from card networks without double-charging, and KYC/AML onboarding flows that must satisfy a compliance officer before a single user goes live. These are the core of the product.
85% of CFOs reported finance talent shortages in the Deloitte CFO Survey, while financial services averages 44.7 days to fill a role, among the longest hiring cycles of any sector in the US. When you hire fintech developers in this market, domain experience becomes the filter that matters more than any other. This applies whether you are looking to hire fintech software developers through a vendor or building an in-house team from scratch.
Compliance You Cannot Fake
Compliance in fintech is a production requirement. A developer who has never worked on a PCI DSS-scoped system doesn’t know where the compliance perimeter sits in the codebase. That means architecture decisions that create audit failures later. You won’t catch this in a standard technical interview.
The competencies that separate a fintech-ready developer from a generic one:
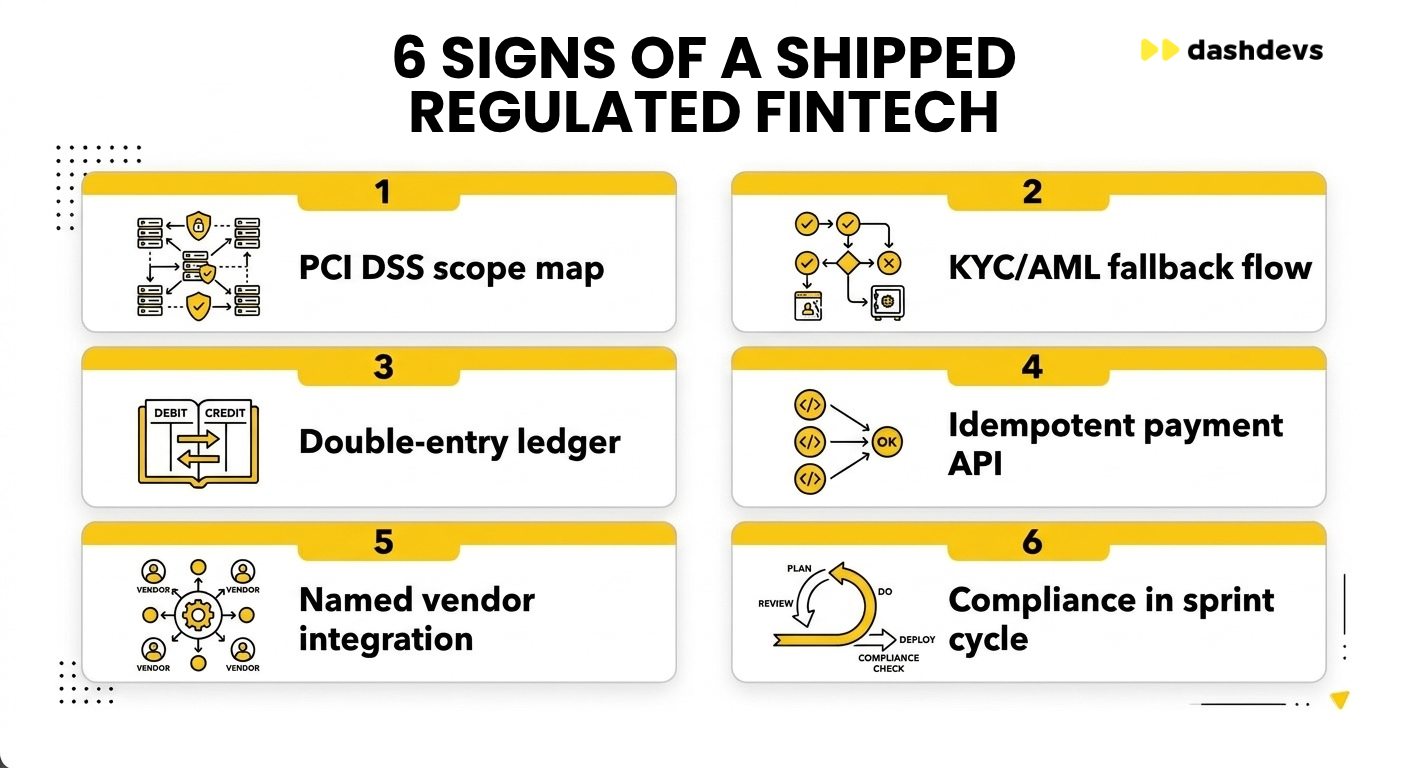
- PCI DSS scope management: Understanding which components enter scope, how to segment card data flows, and what tokenization is required at each layer.
- KYC/AML onboarding flows: Experience building identity verification pipelines that satisfy an MLRO, including fallback logic for document failures and adverse media screening.
- Double-entry ledger design: Every financial product that moves money needs a ledger. A developer who has only worked with single-entry accounting systems won’t understand why every credit must have a matching debit. The bugs that follow aren’t trivial to reverse.
- Idempotent payment APIs: Payment networks retry. A developer who doesn’t build idempotency keys into every payment mutation will ship a product that can double-charge users under network failure conditions.
The compliance perimeter is part of the architecture from day one. Teams that treat it as a final review item before launch typically spend six to twelve months rebuilding what they shipped.
We have rebuilt compliance perimeters for clients who treated it as a final review step. It is always more expensive the second time.
See how we approach the secure software development lifecycle across regulated products for more on this.
Vendor Integration Experience
Most fintech products depend on a network of third-party providers: a card issuer, an open banking aggregator, a KYC vendor, and a payment scheme. Each integration carries its own API contracts, rate limits, failure modes, and data formats. A developer without prior experience with these providers will spend weeks on integration problems that an experienced developer resolves in days.
The vendor integrations that appear most frequently across regulated fintech products:
- Card issuers: Marqeta, Galileo, Thredd, Tutuka
- Open banking providers: Plaid, TrueLayer, Yapily, Tink
- KYC/AML vendors: Onfido, Sumsub, Jumio, ComplyAdvantage
- Payment rails: Stripe, Adyen, Worldpay, Modulr
Across 100+ financial products delivered, we have integrated 70+ fintech providers. The pattern that emerges: vendors with similar functions have very different integration complexity. A team without that prior exposure will consistently underestimate the effort.
The Vetting Scorecard
Use this scorecard in technical interviews. Competitors list skills like Python and cloud. These questions test whether a candidate has solved the actual problems fintech produces in production.
| Area | What to ask | Green flag | Red flag |
|---|---|---|---|
| PCI DSS | Walk me through how you scope a card data flow in a microservices architecture. | Names specific components that enter scope, describes the tokenization approach, mentions network segmentation | Says PCI DSS is handled by the payment provider |
| KYC/AML onboarding | How do you handle a document verification failure in an onboarding flow? | Describes fallback logic, manual review queue, MLRO escalation path | Treats KYC as a single API call |
| Double-entry ledger | How do you ensure your ledger reconciles under a partial system failure? | Explains deferred settlement entries, idempotency on posting, reconciliation job design | Hasn’t built a ledger before |
| Idempotent APIs | What happens to a payment mutation when the network drops between request and response? | Describes idempotency keys, retry-safe endpoint design, at-most-once vs at-least-once semantics | Assumes the client will retry correctly |
| Vendor integrations | Which open banking or card-issuer APIs have you integrated, and what surprised you? | Names specific providers, describes a specific integration problem and resolution | Lists providers only without operational detail |
| Compliance posture | How do you keep a development team compliant during a fast iteration cycle? | Mentions compliance checkpoints in sprint planning, security review gates, pen testing cadence | Treats compliance as a final sign-off task |
For the technical interview shortlist, also ask how they handled a ledger reconciliation failure in production, what their approach is to AML transaction monitoring thresholds, and which regulatory changes in the past 12 months affected architecture decisions on their last project.
A developer who answers all six rows above without hesitation has likely shipped a regulated financial product. One who defaults to generic answers on three or more has probably not.
The question of how to evaluate fintech vendors beyond the technical interview is the one that’s highly important. Check out our guide to understand how to do it.
How Much Does It Cost to Hire Dedicated Fintech Developers?
The sticker rate isn’t the real number. Most teams look only at the monthly rate when budgeting for a dedicated fintech team. The actual cost includes the full ramp cycle before a developer contributes production output.
Regional Rate Benchmarks
Rates vary significantly by region. The figures below are market-range benchmarks, not fixed prices, and should be treated as directional. Always request a breakdown by seniority and role when comparing vendors.
| Region | Mid-level backend dev (monthly) | Senior backend dev (monthly) | Source / year |
|---|---|---|---|
| Western Europe (UK, Germany) | 12,000 | 18,000 | Glassdoor / LinkedIn Salary, 2025 |
| Central & Eastern Europe (Poland, Hungary) | 8,000 | 13,000 | Justjoin.it / No Fluff Jobs, 2025 |
| LATAM (Colombia, Argentina) | 7,000 | 11,000 | Deel Global Hiring Report, 2025 |
| South & Southeast Asia (India, Ukraine) | 6,000 | 10,000 | Hired State of Software Engineers, 2025 |
These are gross rates for a single engineer. A fully dedicated team (PM, BA, two backend, mobile, QA, and DevOps) multiplies the total by six to eight before any tooling or infrastructure costs. For a complete picture of what drives the full build cost, see what it really costs to build a fintech app.
The UK’s fintech sector posted a 29% year-on-year increase in professional job vacancies during 2025, substantially outperforming the broader financial services market (Morgan McKinley, 2025). That supply pressure is already pushing rates upward in Western European markets. Eastern Europe and LATAM continue to offer the most competitive access to senior financial software developers with regulated-product experience.
Hidden Costs Most Teams Miss
The total cost includes three categories most RFPs don’t ask about.
- Onboarding lag: A fintech-experienced developer joining a new codebase typically requires four to eight weeks before contributing production-ready code. That window costs full salary with near-zero output.
- Compliance knowledge transfer: For products with PCI DSS scope or live KYC/AML obligations, this transfer takes two to four weeks of dedicated time from senior team members.
- Security review cycles: A penetration test on a financial application costs 50,000 depending on scope and frequency. Remediation adds engineering time on top. Teams that don’t budget for this discover it during the audit.
The total cost for the first six months of a new dedicated fintech developer is typically 1.3–1.6 times the visible rate. Plan for this in the RFP.
How to Set Up a Dedicated Fintech Team?
Setting up a dedicated fintech team follows a four-stage process. Each stage has a defined output. Skipping a stage doesn’t save time. It creates rework in the next one. For a detailed walkthrough of the opening document, see our guide to request for proposal software development.
Step 1: RFP
The RFP determines whether vendors assess the same project or respond to their own interpretation of it. A fintech RFP must specify the regulatory environment, the target markets, the payment rails in scope, and the compliance standards the product must meet.
Vendors who don’t ask clarifying questions about these items at the RFP stage are generalists repricing a template. A strong RFP also names the evaluation criteria explicitly: technical depth, regulatory experience by market, prior integrations with named providers, and team stability metrics.
Step 2: Technical Assessment
The technical assessment determines whether the vendor’s team can build what the RFP describes. The assessment should cover three areas:
- Architecture review: Does their proposed solution design match the compliance perimeter your product requires? Ask for a high-level architecture diagram for a product similar to yours and probe the security decisions specifically.
- Reference check: Ask to speak with a technical lead from a previous fintech client. The questions are how the team handled a compliance issue in production, what the knowledge transfer process looked like at the end of the contract, and whether any architecture decisions were changed on regulatory advice.
- Vetting scorecard: Apply the scorecard from the previous section to the lead engineers being proposed for your team.
Step 3: Team Composition
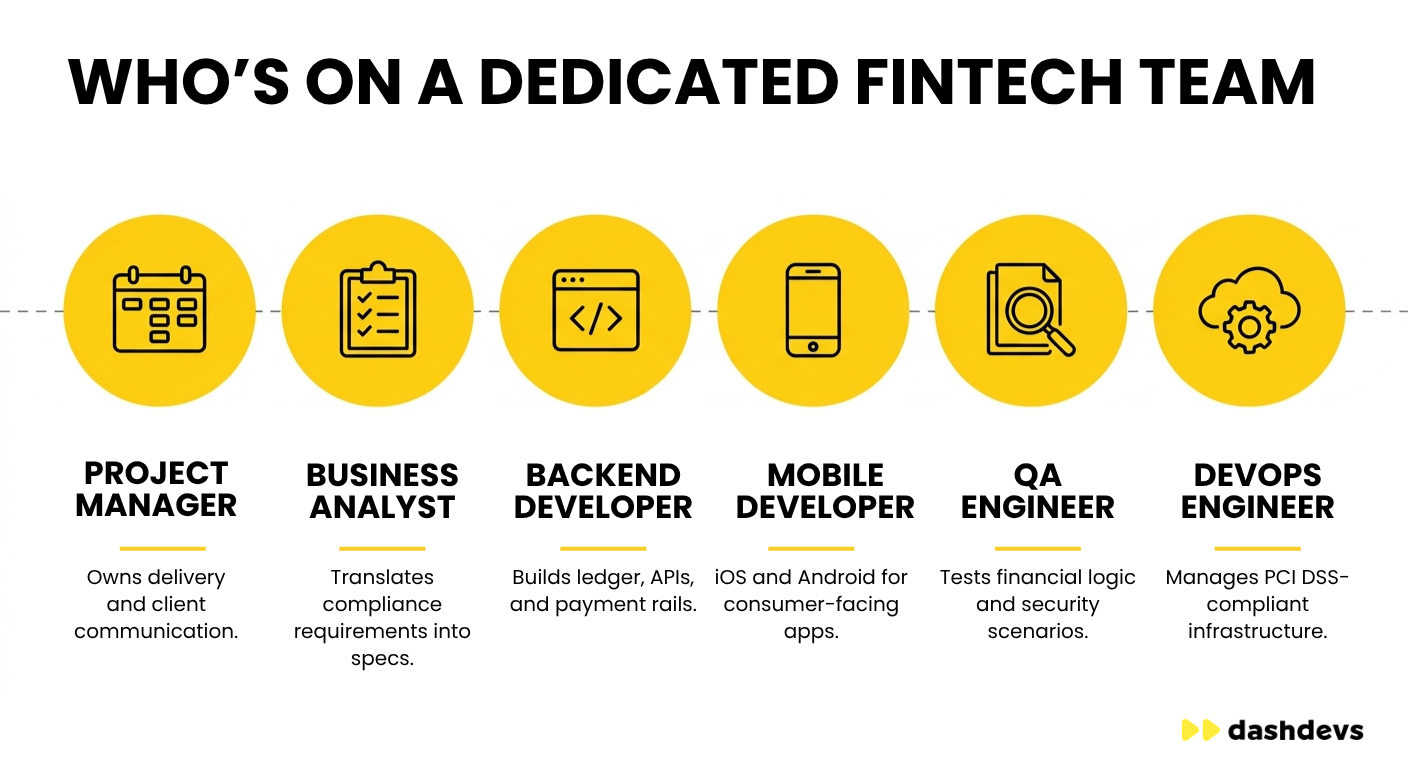
A complete dedicated fintech team for a regulated product typically includes a Project Manager, a Business Analyst, two to three backend developers with fintech domain experience, one or two mobile developers if the product has a consumer app, a QA engineer with financial application testing experience, and a DevOps engineer who understands cloud infrastructure in a PCI DSS or FCA-regulated environment.
The team shouldn’t be assembled before the solution architecture is complete. The architecture determines which competencies are critical on the path and which can be part-time.
For a practical discussion of what happens when product and engineering are misaligned from the start, see why product and engineering misalignment slows fintech teams on Fintech Garden, the fintech podcast by DashDevs.
Step 4: First 90 Days
The first 90 days determine whether the engagement produces a working product or a backlog of architecture decisions that need revisiting. Structure them as three phases.
- Days 1–30: Codebase onboarding, compliance perimeter review, environment setup, and first sprint planning. No production code shipped in this window is a warning sign. It means discovery is still incomplete.
- Days 31–60: First production-ready features shipped. Compliance checkpoints integrated into the sprint cycle. Communication cadence established between client stakeholders and the team.
- Days 61–90: First internal demo or user testing session. Architecture decisions validated against the original specification. Any scope gaps identified and documented before they become change requests.
Dedicated Team on Fintech Core or Building From Scratch?
For teams with a defined product scope, a dedicated team building on Fintech Core changes what engineers spend their time on from day one.
Fintech Core is DashDevs’ composable fintech infrastructure and orchestration platform for launching, expanding, or modernizing regulated financial products. It gives teams a faster starting point than a custom build, with more flexibility and control than traditional white-label or SaaS platforms.
The standard problem when building from scratch: a significant portion of early engineering time goes toward infrastructure that every regulated financial product needs. It’s a ledger, KYC/KYB flows, card issuing connectors, an AML toolkit, and transaction processing. None of that is product differentiation. It is table stakes that takes three to six months to build correctly.
A dedicated team operating on Fintech Core skips that foundational build and focuses on the product logic, user experience, and provider integrations that create actual competitive advantage. The platform is typically 12 weeks into production, compared to eight to twelve months for an equivalent build from scratch.
The team that has done it before moves faster because they aren’t solving infrastructure problems for the first time.
This model isn’t right for every product. Teams that have a strong reason to own every layer (specific regulatory requirements, a proprietary ledger design, or deep technical IP) should build from scratch. For most fintechs, the question is whether the infrastructure is the product or the foundation for it.
How does it look in practice?
Three partnerships from our delivery record illustrate what the dedicated team model produces at different stages.
PayTile: outstaffing model at scale
- Product: US-based private digital wallet featuring geolocation-based payments and physical retail reward drops.
- The Challenge: Engineer anonymous, privacy-focused payment flows while remaining compliant with federal and global KYC/AML standards.
- Our Scope: Provided an outstaffing team of front-end and back-end engineers working alongside PayTile’s internal team across iOS, Android, core back-end architecture, and third-party API integrations.
Key Results:
- 5M+ active users worldwide
- 4.5+ star average rating across iOS and Android App Stores
- Delivered a fully compliant, privacy-centric payment architecture
See how we extended PayTile’s team as an outstaffing partner
Chip: 3+ year partnership on a regulated savings platform
- Product: UK-based, AI-powered savings and investment platform regulated under FCA obligations.
- The Challenge: Build a compliant Open Banking core engine while maintaining rapid feature deployments across three distinct codebases under strict PCI DSS standards and multi-bank integrations.
- Our Scope: Solution architecture, native iOS and Android development, back-end engineering, QA, and project management.
Key Results:
- 3 months to deliver the initial production MVP
- 500K+ active users reached
- £45M total funding raised
- 3+ years of continuous, multi-app feature delivery
The Chip partnership worked because compliance was a shared concern from day one, not a handoff at the end of each sprint.
Read the full 3+ year Chip partnership breakdown.
Dozens: UK digital bank delivered in 9 months
- Product: Full-fledged UK challenger bank operating under dual FCA licenses.
- The Challenge: Assemble a complete, production-ready engineering team within weeks under strict FCA launch deadlines.
- Our Scope: Core engineering team delivery across custom cloud-native banking core, 20+ ecosystem integrations (KYC, card issuing, fraud detection), and mobile apps.
Key Results:
- 9 months from concept to live, fully licensed retail bank launch
- 60,000+ customers acquired
- £35M in funding secured
- Zero compliance breaches across operations
All three cases reflect the same pattern: a dedicated team that understands the product domain reduces the coordination overhead that kills timelines in regulated fintech.
Is a Dedicated Team the Right Call?
A dedicated team is the right structure when the product requires compliance accountability, sustained velocity, and specialist knowledge that would take 12+ months to source in-house. If you decide to hire dedicated fintech developers through a vendor partner, the criteria below tell you when that choice is the right one. If you are weighing this against trying to hire a fintech developer in-house, the same criteria apply in reverse. The criteria are straightforward.
Choose a dedicated fintech team if:
- Your product operates in a regulated environment (PCI DSS, FCA, EMI, PSD2, or equivalent).
- You need a vendor who shares accountability for compliance.
- The build will run for 12 months or longer, making knowledge retention a competitive factor.
- Your internal team lacks the domain experience to evaluate the technical decisions the vendor will make.
Choose in-house hiring if your company already has a fintech engineering function, an internal compliance lead, and the runway to absorb a 3–6 month senior hire cycle without delaying the roadmap. Teams building consumer-facing products can explore dedicated fintech app development services or banking software developers depending on the product type.
Choose staff augmentation if you have a strong internal PM and a defined short-term skills gap.
The decision comes down to one question: does the work require someone accountable for the outcome, or someone who executes against a brief you control? For most regulated financial products, accountability is worth more than flexibility.
Share article
