


Merchant Acquiring for Ecommerce: How the Acquiring Layer Actually Works

October 21, 2026
- Merchant acquiring is the licensed service that holds the merchant contract, routes card transactions through Visa and Mastercard, and settles funds.
- The discount rate has three layers: interchange, scheme fees, and acquirer markup. Only the markup is negotiable.
- A PSP, direct acquirer, PayFac, and multi-acquirer setup each trade control for speed. The right one depends on volume and whether you must own the merchant contract.
- Local acquiring and smart routing move authorization rates. Failover recovers system-unavailable declines a single acquirer would lose.
- Rolling reserves and the pricing model should be negotiated before the contract is signed.
Merchant acquiring is the licensed financial service that holds your merchant contract, routes card transactions through Visa and Mastercard, and settles money into your account. The acquirer is the entity that actually carries the risk and determines your cost structure. This article covers how acquirers earn, what drives fees inside the discount rate, and how to choose between a direct acquirer, PSP, PayFac, and multi-acquirer setup.
Which model fits your business?
| Your situation | Start here |
|---|---|
| Early-stage, sub-$1M GMV | PSP / aggregator |
| Platform with sub-merchant payouts | PayFac |
| High-risk vertical | Specialist acquirer |
| High-volume SaaS or subscription | Direct acquirer + IC+ |
| Multi-region, 8-figure+ GMV | Multi-acquirer orchestration |
The full breakdown with decision criteria is at the end of this article.
What Is Merchant Acquiring?
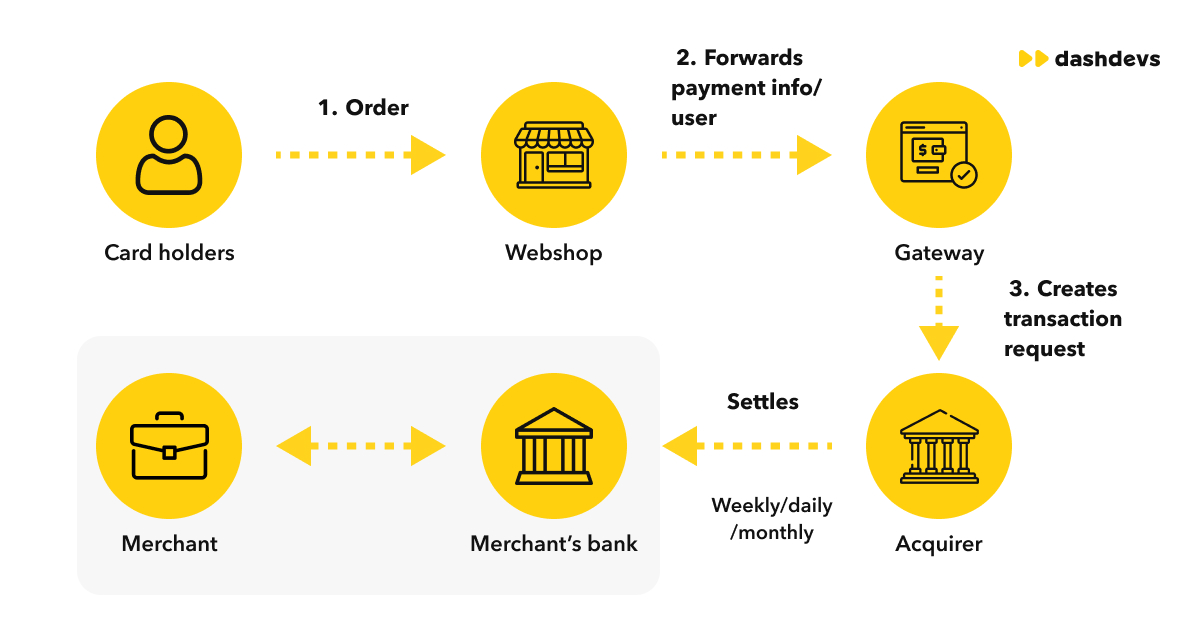
The acquirer does three things most people assume someone else handles:
Onboarding and underwriting. The acquirer evaluates your business model and chargeback history, along with industry category and risk classification, before granting a merchant account. This is why high-risk verticals (travel, online gaming, digital goods, subscription businesses) face stricter scrutiny and higher initial deposit requirements.
Transaction routing and settlement. The acquirer submits authorization requests to card networks, receives approval responses, batches cleared transactions, and deposits net proceeds into your account, typically within T+1 to T+3 of the transaction date.
Risk and liability. The acquirer carries the chargeback liability for every transaction processed through your account. If a merchant can’t cover chargebacks or goes out of business mid-dispute, the acquirer is financially responsible.
For teams who want to understand how to accept payments on your website before going deeper into the acquiring layer, the setup decisions start earlier, but the acquiring relationship is what determines the economics and risk profile of the entire stack once you’re processing volume.
Merchant Acquirer vs Payment Processor vs Payment Gateway vs PayFac
These four entities are routinely conflated in technical discussions, even by developers who’ve built on top of them. The payment processor vs payment gateway distinction is one layer of the confusion; the acquirer and PayFac add two more. Understanding who holds what in each model is the prerequisite for every other acquiring decision.
| Entity | Holds merchant contract | Carries chargeback liability | Settles funds | Typical fit |
|---|---|---|---|---|
| Merchant acquiring platform | Yes, directly | Yes | Yes | Enterprises, direct licensees |
| Payment processor | No | No | No — routes transaction data only | Works under acquirer |
| Payment gateway | No | No | No — captures and tokenizes only | Technical front-end for any acquirer |
| PSP / PayFac | Aggregated master merchant | Shared / sub-merchant level | Yes, via master account | SMBs, marketplaces, platforms |
The practical implication: if you’re a merchant who signed with a PSP, you’re a sub-merchant on the PSP’s master merchant account. That’s a reasonable trade at low volume. At scale, it limits your pricing model, dispute control, and ability to optimize approval rates.
How Does a Card Transaction Actually Flow?
Most teams have an approximate mental model of card transactions. The details matter because each step is where fees accumulate and where authorization rates can be influenced. Understanding the flow is the prerequisite for designing any custom acquiring or payment orchestration layer.
Here’s the full sequence for a card-not-present ecommerce transaction:
- Customer submits payment. The payment gateway tokenizes the card data and forwards an authorization request downstream to the acquirer. Teams who need to understand the full technical scope can read DashDevs’ guide on how to build a payment gateway from scratch.
- Acquirer submits to the card network. The merchant acquiring platform sends the authorization request to Visa, Mastercard, or Amex, including the merchant category code (MCC), transaction amount, and card BIN data.
- Card network routes to the issuing bank. Visa or Mastercard routes the request to the bank that issued the customer’s card.
- Issuing bank makes the authorization decision. The issuer checks available funds, applies fraud scoring, evaluates the 3DS2 authentication result, and returns an approval or decline. Hard declines (e.g., insufficient funds, stolen card) are issuer-level rejections that retrying will not fix. Soft declines (where the issuer or network is temporarily unavailable) can be recovered with retry or failover logic.
- Response returns downstream. Authorization response passes back through the card network, acquirer, gateway, and merchant. The round-trip typically completes in under two seconds.
- Clearing. At the end of the day, the merchant (or acquirer on its behalf) batches all approved transactions and submits them for clearing through the card network.
- Settlement. The issuing bank transfers funds to the acquirer. The acquirer deducts its fees, then credits the net amount to the merchant’s account.
This is how the transaction processing system layer connects to the acquiring relationship. For merchants scaling e-commerce payment processing across borders, steps 2–4 are where routing decisions most affect approval rates, covered in the cross-border section below.
What Does Merchant Acquiring Actually Cost?
Every acquiring fee is built from three layers. Most merchants only see a single blended rate, which hides the structure. Understanding what drives credit card processing costs is how you evaluate whether a rate is actually competitive and where negotiation is possible.
Layer 1: Interchange. Set by the card networks (Visa, Mastercard, Amex) and non-negotiable. Interchange varies by card type (consumer debit vs commercial credit), market (EU interchange is capped by regulation; US rates are substantially higher), and channel (card-present vs card-not-present). Interchange is collected by the issuing bank on each transaction.
Layer 2: Scheme fees. Charged by the card networks for access to their infrastructure. Smaller than interchange but present on every transaction, and published annually in Visa and Mastercard’s fee schedules. Includes authorization fees, service fees, and network access fees.
Layer 3: Acquirer markup. The acquirer’s commercial margin, applied on top of interchange and scheme fees. This is the negotiable component, where pricing models diverge significantly.
Pricing models:
| Model | What the merchant sees | What’s transparent | Typical fit |
|---|---|---|---|
| Blended / flat rate | Single % + fixed fee per transaction | Rate only | Low-volume merchants; early-stage |
| Interchange-plus (IC+) | Interchange + fixed acquirer markup | Interchange and markup separated | Mid-market merchants |
| Interchange++ (IC++) | Interchange + scheme fees + markup, each as a separate line | All three layers | Enterprise direct acquirer contracts |
Blended pricing looks simple. At scale, it just means you’re funding someone else’s margin without knowing it.
Most PSPs default to blended pricing, which is appropriate when simplicity is the priority. As monthly card volume grows into seven figures, the delta between blended and IC+ pricing becomes worth quantifying seriously.
Which Acquiring Model Is Right for Your Business?
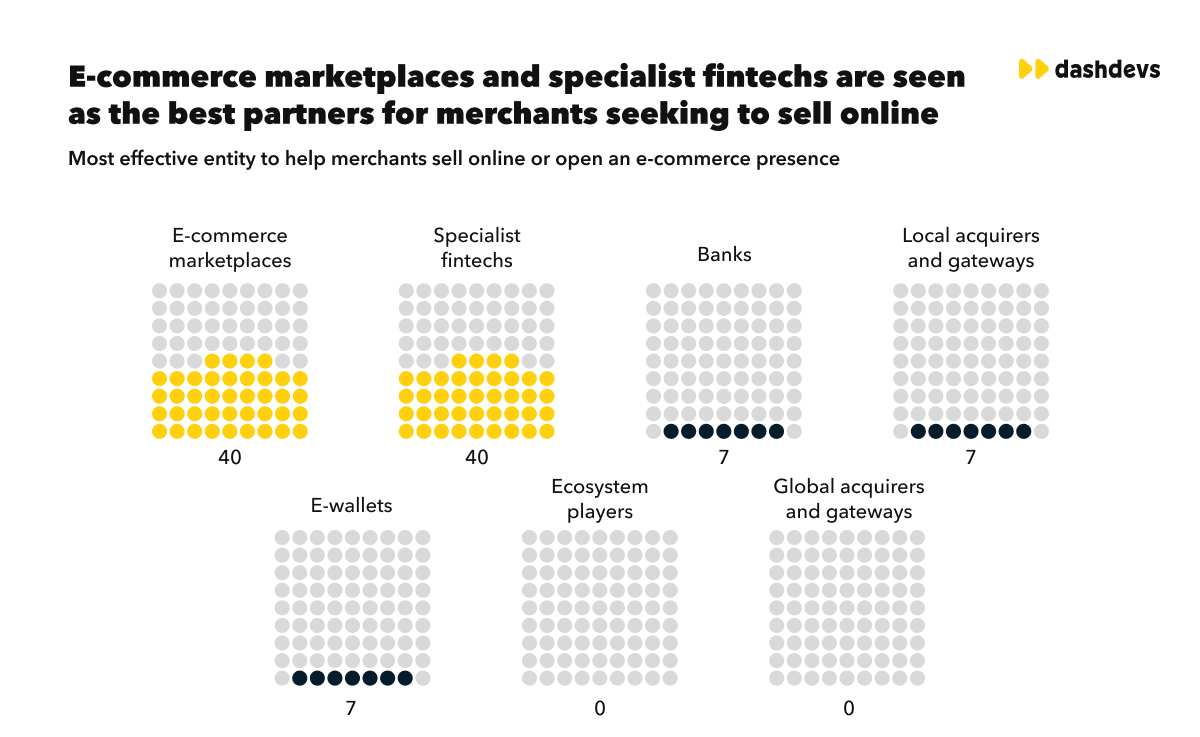
This is the decision most teams get wrong because they default to the fastest path at launch without modeling what they’ll need at scale. Each model trades control for simplicity differently.
Direct acquirer. A bilateral relationship between the merchant and a licensed acquiring bank. The merchant goes through full underwriting, signs a merchant service agreement, and gets access to IC+ or IC++ pricing and direct settlement. Control is maximum; setup time runs four to twelve weeks (more for high-risk categories). Best for established merchants with consistent transaction volume and the operational capacity to manage the relationship directly.
PSP / aggregator. The PSP holds a master merchant account, and sub-merchants operate under it. Onboarding is fast, sometimes instant for low-risk merchants. Pricing is typically blended. If the PSP freezes or terminates the account, the merchant has limited recourse. Best for early-stage or lower-volume merchants where simplicity outweighs control.
PayFac (payment facilitator). Platforms that need to onboard and pay out sub-merchants register as PayFacs to control the full onboarding and settlement flow. The platform takes on KYC/AML responsibility for its sub-merchants. Our article on how the payment facilitator (PayFac) model works covers the licensing and liability structure in detail, including why it’s not appropriate for merchants who simply want better pricing.
Multi-acquirer orchestration. A routing layer that distributes transactions across multiple direct acquirer relationships in real time, based on geography, card type, transaction cost, and historical approval rates by acquirer. Highest setup complexity; highest potential return on authorization rate and fee optimization. Not a first-move option, but the right architecture for enterprise and multi-regional merchants above a certain volume threshold.
| Model | Time to live | Fee visibility | Chargeback control | Approval rate optimization |
|---|---|---|---|---|
| Direct acquirer | 4–12 weeks | IC+ or IC++ | Direct | Limited (single acquirer) |
| PSP / aggregator | Hours to days | Blended | Via PSP dispute process | Limited |
| PayFac | 4–8 weeks to build | Custom per sub-merchant | Platform controls | Limited |
| Multi-acquirer | 3–6 months to build | Mixed | Direct per acquirer relationship | High |
The segment-to-option map at the end of this article translates these models into specific starting recommendations by business type.
Does Your Acquiring Setup Affect Authorization Rates?
Yes, directly. Authorization rate is one of the most consequential metrics in a payment stack and one of the most underoptimized. Three mechanisms in the acquiring setup determine how much headroom you have:
Local acquiring. A card issued in Germany, processed through a local German acquirer, will typically see a higher approval rate than the same card processed cross-border through a UK acquirer. Issuing banks apply stricter fraud rules to foreign-acquirer transactions, particularly for card-not-present ecommerce flows where local issuer behavior patterns are harder to model cross-border. For merchants selling into multiple markets, local acquiring relationships in key geographies improve authorization rates more than most other optimization levers.
Smart routing. Multi-acquirer routing sends each transaction to the acquirer most likely to approve it based on card BIN, card network, currency, transaction amount, and historical approval data by the acquirer. For high-volume merchants with a multi-regional customer base, routing optimization can move authorization rates by several percentage points. The routing logic needs to be dynamic, not a static rule set, because issuer behavior and acquirer performance change over time.
Failover. When the primary acquirer returns a system-unavailable decline rather than a hard decline, a fallback route to a secondary acquirer can recover the transaction without the customer knowing. For cross-border payment processing at an enterprise scale, failover is close to non-negotiable; scheduled maintenance windows and unexpected acquirer downtime costs real revenue.
For the iOL Pay platform, our payment acceptance solution for global hospitality, we designed a multi-method acquiring infrastructure supporting 250+ payment methods across 23,000+ hotels worldwide. The routing logic handles significant diversity in card type, currency, and geographic origin within a single transaction flow, with failover built into the core architecture rather than layered on afterward.
What Should You Verify Before Signing With an Acquirer?
The evaluation criteria for a direct merchant acquiring relationship are different from those for a PSP integration. A merchant service provider selection is partly a commercial decision and partly an engineering one. The criteria missed in diligence are usually the ones that cause operational problems six months after launch.
| Criterion | What to verify | Why it matters |
|---|---|---|
| Integration compatibility | API documentation quality, sandbox environment, SDK availability | Determines your go-live timeline and long-term integration maintenance burden |
| Supported payment methods | Card networks, digital wallets, local payment methods by market | Customer conversion drops when preferred payment methods aren’t available at checkout |
| Geographic and currency coverage | Countries where you’re registered vs markets where you sell | A UK-registered merchant selling into 12 EU markets needs acquirer coverage for all 12 |
| Fee structure and pricing model | All-in breakdown: interchange, scheme fees, acquirer markup; pricing model | Blended rates can obscure 30–50 bps of cost at high volume; confirm IC+ or IC++ availability |
| Chargeback and dispute process | Liability thresholds, dispute timeline, per-chargeback fees, representment support | Chargeback ratios above 0.9% can trigger Visa’s monitoring programme; Mastercard’s threshold is 1% |
| 3DS2 and fraud tooling | 3DS2 mandate coverage, how the 3DS2 liability shift protects merchants, tokenization support | Properly authenticated 3DS2 transactions shift chargeback liability to the issuing bank — a significant risk transfer |
| Settlement timing and reserve terms | T+1, T+2, T+3 windows; rolling reserve percentage and release schedule | Rolling reserves of 10% held for 90–180 days affect working capital significantly for growth-stage merchants |
| PCI DSS certification | Level 1 PCI DSS certification; shared-responsibility model for CNP environments | Required for any environment that touches card data. Confirm scope boundaries early |
| Recurring transaction support | Network tokenization, token-based recurring billing, mandate management | Essential for subscription, SaaS, and marketplace payout flows |
| Client references in your vertical | Named clients in your industry or geography | Underwriting surprises and MCC restrictions are most common when acquirers lack experience in your category |
Watch-outs: acquirers who can’t provide named client references in your vertical are a material risk when entering new markets or high-risk categories. Rolling reserve terms are rarely negotiated proactively, and they should be, before the contract is signed rather than at renewal.
Rolling reserves are always negotiable before signing. Almost never after.
For card-not-present environments, also confirm whether the acquirer supports address verification service (AVS) as part of their fraud tooling stack.
What Does a Production Acquiring Infrastructure Look Like?
We treat acquiring as a product architecture decision, not a vendor selection. The model, fee structure, and routing logic get designed into the system early because refactoring the acquiring layer at scale is significantly more expensive than getting it right in the initial build.
iOL Pay: a global hospitality payment platform
Illusions Online’s payment subsidiary serves 23,000+ hotels worldwide. The client needed global payments, virtual cards, merchant wallets, remittances, and FX consolidated into one platform. We built a multi-method payment acceptance layer supporting 250+ payment methods, with iOL Pay operating as the merchant of record. One-click booking with card tokenization improved conversion directly. Global acquiring integrations eliminated the manual processing overhead hotels had previously absorbed.
Licensed PSP: payment orchestration at scale
One of our PSP clients runs a payment orchestration platform handling 10,000+ payment requests per second. The architecture uses real-time BIN-level routing across multiple acquiring relationships, with automatic failover built into the core layer rather than added on afterward.
MuchBetter: multicurrency e-wallet
An award-winning e-wallet available in 180+ countries, serving 400K+ users and 300+ merchants. The infrastructure handles multi-currency settlement complexity at significant cross-border volume. Different operational profile from hospitality, same underlying principle: the acquiring layer determines what’s possible.
We’ve integrated with 70+ fintech vendors across 15+ years in regulated fintech delivery, including direct acquirer relationships, PSP-layer implementations, and payment orchestration builds. Our fintech integration services cover the full acquiring integration scope: acquirer API integration, reconciliation, dispute workflow, settlement reporting, and ongoing operational support.
For teams building inside a licensed PSP, EMI, or payment institution, this is also where infrastructure for licensed PSPs and EMIs becomes relevant. We’ve used Fintech Core by DashDevs modules to compress the standard acquiring integration timeline for licensed institutions that need to go live without rebuilding the settlement and reconciliation stack from scratch.
Where should you start?
The fastest way to narrow the options is to decide whether you need to own your merchant contract directly or whether aggregated pricing still works at your volume. Everything else follows from that answer.
| Business type | Recommended starting model | Key reason |
|---|---|---|
| SMB ecommerce, sub-$1M GMV | PSP / aggregator | Speed to market; blended pricing is acceptable and cost-efficient at this volume |
| Marketplace or platform with sub-merchant payouts | PayFac model | Sub-merchant onboarding and split settlement are native to the PayFac structure |
| High-risk vertical (travel, online gaming, forex, digital goods) | Specialist high-risk merchant acquiring solutions | Standard PSPs restrict or decline high-risk MCCs; specialist acquirers price for the risk explicitly and build dispute management into the relationship |
| High-volume SaaS or subscription business | Direct acquirer + IC+ pricing | Volume justifies a direct relationship; recurring billing requires robust network tokenization and mandate support |
| Multi-region enterprise, 8-figure+ GMV | Multi-acquirer orchestration | Approval rate optimization, FX management, and regulatory redundancy all require multiple direct acquirer relationships with intelligent routing across them |
If you’re evaluating payment processing companies for the first time or reassessing an existing stack, that 18-month question is the right frame.
Share article
