


What Is a Transaction Processing System (TPS): Types, Components & Examples

October 15, 2026
- A transaction processing system is the software layer that validates, executes, posts, and reconciles every business event. It governs data before and after it reaches an external rail.
- The costliest TPS failures in production aren't outages. They stem from duplicate postings, silent reconciliation drift, and unmitigated idempotency gaps under volume.
- Most licensed fintechs and banks run hybrid processing models. They combine real-time authorization for users, batch settlement for clearing, and continuous reconciliation.
- DashDevs has engineered payment orchestration platforms handling up to 10,000 concurrent payment requests per second. A unified ledger tracks flows across rails and currencies.
- Build vs buy in TPS architecture isn't binary. Fintech Core compresses a 12-month custom TPS build into 3 months while preserving ledger flexibility and compliance controls.
- ACID properties aren't mere database theory in a TPS. They form the contractual baseline required to audit, replay, and justify payment events to regulators.
When a customer taps to pay, the card network doesn’t own what happens next. The card network moves the message. Your transaction processing system owns the outcome. That covers the balance update, the ledger post, and the record an auditor can read six months later.
That distinction matters more than most teams realize until production pressure exposes it. A TPS that works under low volume can look complete. An end-of-month batch or a campaign spike then reveals idempotency gaps, duplicate postings, or reconciliation drift. Finance had been patching that by hand.
This guide is for product and engineering leaders at licensed fintechs, EMIs, and banks. They are designing, selecting, or modernizing payment infrastructure. They need a practical framework.
It draws on DashDevs delivery across payment orchestration, digital banking, trading platforms, and Fintech Core. The architecture decisions inside a TPS shape commercial outcomes later.
TPS Definition: What the System Actually Does
A transaction processing system is an operational software layer that validates, executes, posts, and reconciles transactions for licensed fintechs, EMIs, and banks. Each event completes once, is recorded accurately, and stays consistent across dependent systems.
The short name is TPS, and TPS systems add integrity, concurrency control, and failure semantics. That sits on top of a basic database or reporting pipeline. A transaction information system usually emphasizes data capture and analytics. A full TPS enforces business rules, atomic updates, and recovery. That is what makes the stored data trustworthy.
A TPS doesn’t move funds across card networks, ACH, wires, or blockchains. It orchestrates, validates, and records the transactions that flow through those rails. Where the rail ends and internal processing begins is an early architecture choice. The payment processor vs payment gateway distinction draws that boundary.
What makes a TPS different from a reporting system is behavior under failure. A timeout, a partial write, or a duplicate retry will happen. A TPS is designed to detect and handle those conditions deterministically. A reporting system reads what a TPS wrote.
How the Six-Stage Path Works
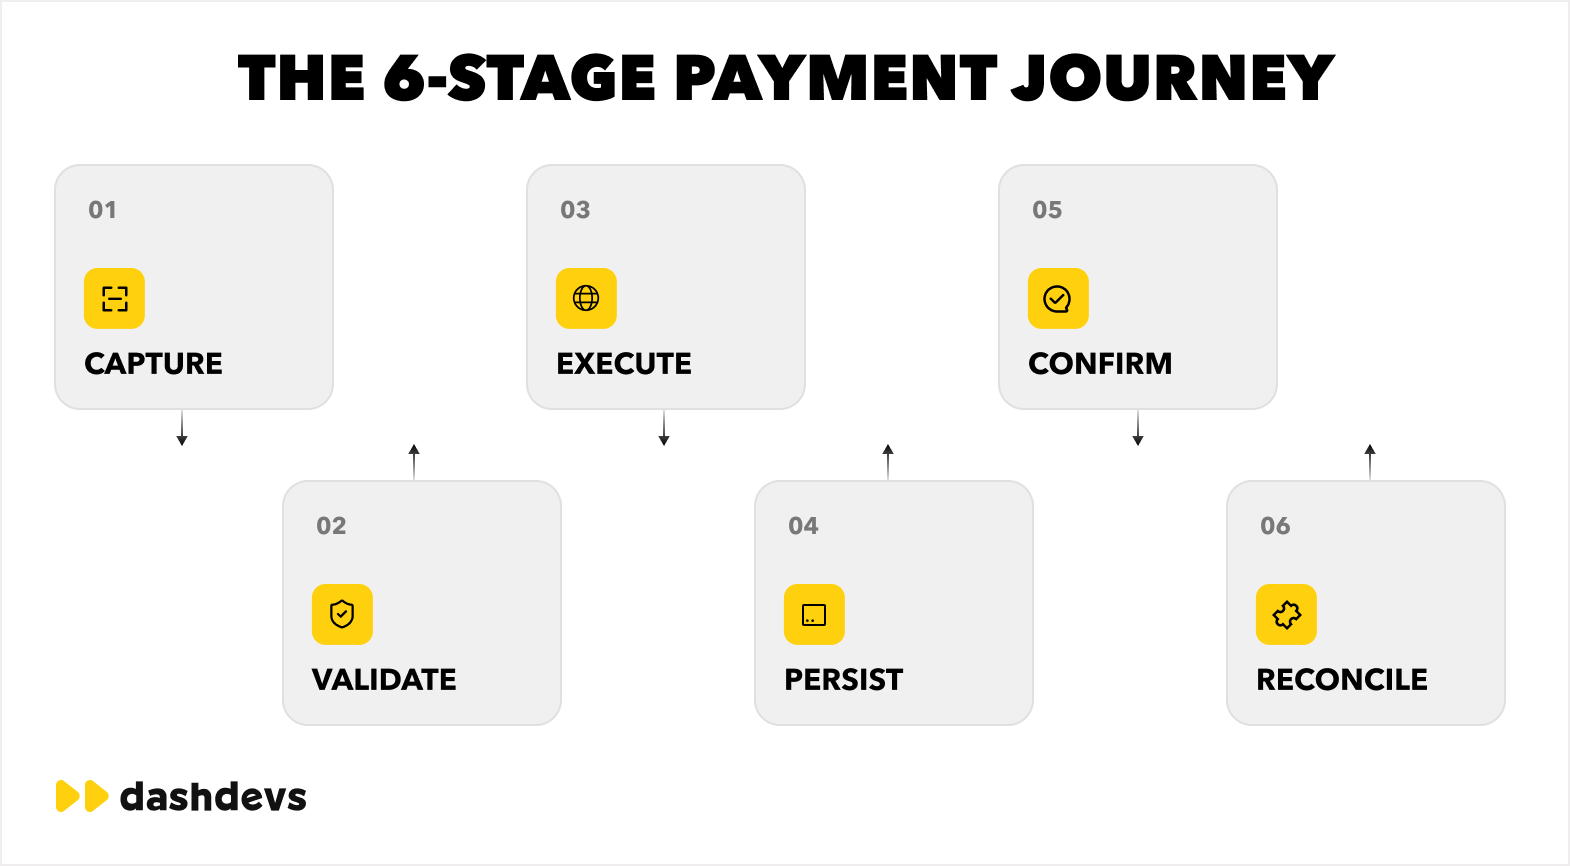
Every payment or account change follows the same six-stage path through a well-designed TPS. Understanding this flow reveals where most production failures originate.
Real-world scenario. A customer initiates a cross-border transfer. The instruction arrives as a structured API request. The transaction processing unit validates account status, KYC state, and transfer limits, then acquires a lock on the source balance. Business rules run: FX rate applied, AML screen triggered. If all checks pass, the ledger posts atomically, the event emits to downstream systems, and the customer receives confirmation. Hours later, the correspondent bank settles. The TPS reconciles that settlement against its own records and closes the loop.
| Stage | What happens |
|---|---|
| Capture | Accept structured input: amount, accounts, and idempotency key |
| Validate | Apply limits, KYC state, sanctions, balance, or trading constraints |
| Execute | Run business rules, coordinate locks, and call external rails if needed |
| Persist | Commit to ledger or database; emit events to downstream systems |
| Confirm | Return user-facing status; feed reporting pipelines |
| Reconcile | Match provider statements; resolve exceptions; retain evidence |
The most expensive TPS failure modes live between stages. When executing calls to an external rail but the persist fails before committing, the customer may already see success. The ledger never recorded that transaction. Idempotency keys and outbox patterns close that gap.
ACID in practice. ACID (atomicity, consistency, isolation, durability) is not an abstract theory inside a TPS. Atomicity means the ledger post and the rail instruction either both happen or neither does. Consistency means business rules run on both paths. Isolation means two concurrent requests to the same balance do not overwrite each other. Durability means a confirmed transaction survives a restart or availability zone failover.
Real-time payment reconciliation is the discipline that detects drift between the TPS record and the scheme. Treat that drift as a production incident, not as accounting clean-up.
Real-Time, Batch, and Hybrid Models
How work runs determines customer experience, operational cost, and reconciliation complexity.
Online Transaction Processing
- Mechanism: OTP processes each event the moment it arrives.
- Applications: This is the model powering card-present purchases, instant payment schemes, trading platforms, and any flow where “pending” is commercially unacceptable.
- Operational Impact: That model demands always-on capacity, circuit breakers, and tight SLAs on the transaction processing unit. The engineering overhead is real, and so is the commercial advantage. Real-time balance visibility and instant confirmation are table stakes for modern fintech products.
Batch Processing
- Mechanism: Batch processing groups events and processes them on a schedule: hourly, nightly, or end-of-cycle.
- Use Cases: Payroll, interest accrual, card network settlement files, and large-scale reconciliation extracts are the classic use cases.
- Trade-offs: Batch is economical for high-volume work where immediacy isn’t required. It turns brittle when upstream real-time systems change format or settlement timing without notice.
OLAP vs OLTP Architecture
- Context: OLAP vs OLTP. Online analytical processing (OLAP) is often conflated with OLTP in architectural discussions about TPS. They serve different purposes.
- OLTP Profile: OLTP is transactional: write-heavy, row-level operations optimized for fast individual reads and writes.
- OLAP Profile: OLAP is analytical, read-heavy, columnar storage optimized for aggregation and reporting.
- Integration Rule: A well-designed TPS feeds an OLAP layer. It doesn’t replace it.
Hybrid Models
- Adoption: Hybrid models are what most licensed banks and fintechs actually run.
- Authorization & Settlement: Real-time authorization gives customers an immediate decision. Settlement, clearing, and posting run on the rail’s own cadence. That cadence may be batch, T+1, or near-instant, depending on the scheme.
- State Governance: The TPS must model pending, authorized, posted, and settled states explicitly. The customer-facing balance and the finance ledger mustn’t contradict each other.
Payment systems spanning SEPA Instant, UK Faster Payments, ACH, and SWIFT need a TPS for each rail’s timing. Don’t collapse those timings into one state machine. Multi-rail payments in Europe cover how state rules vary across schemes. The architectural implications grow when a team runs several corridors.
Types of Transaction Processing Systems
Beyond the real-time, batch, and hybrid axis, transaction processing systems are also categorized by deployment model and tenancy structure.
Streaming and event-driven TPS process each event as a message in a durable queue or event stream. This pattern suits fraud pipelines, market-data limits, and high-fan-out alerts. Many downstream consumers need to react to each transaction. Payment orchestration platforms often coordinate authorization, routing, retry, and ledger posting. They do that across services that deploy on their own.
Geo-partitioned TPS route transactions to processing infrastructure in the same jurisdiction as the customer or data. GDPR data residency requirements, local licensing mandates, and latency to local users are the common drivers.
Multi-tenant SaaS TPS serve multiple client organizations from a single logical platform, with per-tenant isolation, fee structures, and compliance configurations. This is the model behind BaaS providers and embedded finance platforms that need noisy-neighbor controls without separate infrastructure per customer.
| Pattern | When teams adopt it |
|---|---|
| Streaming / event-driven | High fan-out, fraud pipelines, and market data-driven limits |
| Geo-partitioned | Data residency mandates, local licensing, latency requirements |
| Multi-tenant SaaS | BaaS platforms, embedded finance, EMI-as-a-service |
Components of a transaction processing system
The four classic parts, input, processing, storage, and output, describe the shape. In production, two more layers decide whether the system survives scale and a regulatory audit. Those layers are integration adapters and observability.
Input / ingress. APIs, ISO 20022 messages, partner batch files, or signed webhook payloads. The ingress layer validates schema, enforces message authentication, and assigns idempotency keys. Unsigned webhooks and unbounded payload sizes are the most common failure surfaces at this layer.
Transaction processing unit (TPU). The logic layer that validates, sequences, and applies business rules before balances commit. Limits run here. Sanctions checks fire here. FX rates apply here. In distributed architectures, the TPU may span multiple microservices. The contract stays one atomic outcome, coherent at the ledger boundary. What the ledger in banking records is and how it is structured follows from every TPU decision.
Ledger / store of record. The authoritative source of balances and transaction history. This isn’t the reporting database. It is the system finance and compliance read from. Shadow spreadsheets become the real system only when the ledger is poorly structured or inaccessible. For multi-product environments, ledger architecture for multi-product banks covers the design of one ledger. That ledger handles wallets, FX, cards, and lending without structural coupling.
Output / egress. Confirmations, receipts, settlement files, regulatory reporting extracts, and event streams to downstream systems. The most common output failure is a confirmation while finance never updates. The cause is a missing event-bus write or a failed async job.
Integration adapters. The mapping layer between the internal TPS model and external rails: card schemes, SWIFT, ACH, RTP, and crypto custodians. Silent data transformations that break reconciliation are the primary risk.
Observability and evidence. Structured logs, distributed traces, SLO dashboards, and evidence packs for audit. Correlation IDs must span the path from API request to settled record. That is the minimum audit surface for any regulated product.
| Component | Role | Typical failure if underspecified |
|---|---|---|
| Input / ingress | APIs, files, ISO messages | Schema drift, unsigned webhooks, duplicate submissions |
| Transaction processing unit | Validates, sequences, applies rules | Double spends, race conditions, inconsistent fees |
| Ledger / store of record | Authoritative balances and postings | Shadow spreadsheets become the real system |
| Output / egress | Confirmations, receipts, events | Customers informed; finance never updated |
| Integration adapters | Mapping to PSPs, cores, blockchains | Silent transformations that break reconciliation |
| Observability | Logs, traces, metrics, evidence packs | Audits fail despite a working UI |
Characteristics: What Makes a TPS Production-Grade
What separates a mature TPS from a fragile pipeline is measurable. These characteristics are how a TPS earns the trust of finance, risk, compliance, and operations.
Performance and predictability. Low latency for interactive flows is a customer-facing requirement. Predictable throughput under peak load is an operational one. p95 and p999 latency on the transaction processing unit matter more than averages. Partners and schemes benchmark tail performance. Start that comparison by comparing payment processing companies.
Correctness. Atomicity and consistency mean the full outcome commits, or the customer sees a controlled failure. There are no half-posted ledger entries. Isolation means concurrent updates to the same balance don’t silently overwrite each other. This is where optimistic locking, serializable transaction slices, or ledger-side sequencing become architecture decisions rather than implementation details.
Durability and idempotency. After confirming success, a restart or availability zone failover mustn’t lose the transaction. Retries from clients and webhooks are normal operating conditions. Every write path must tolerate duplicates without double-processing. A double charge is the failure mode users never forgive.
Auditability. A transaction that can’t be traced end-to-end by a correlation ID isn’t production-grade. Every material state change must be attributable: who requested it, when, through which interface, and with what outcome. For regulated products, this is a license condition. For real-time data processing pipelines, the same rules decide if the data can be trusted. That applies to operational decisions.
Duplicates are a bigger risk than downtime: users forgive latency; they rarely forgive double charges.
| Characteristic | Example KPI |
|---|---|
| Speed | p95 authorization latency; end-to-end “money good” latency |
| Reliability | Successful transaction rate; error budget burn rate |
| Correctness | Reconciliation difference within threshold; zero unexplained duplicates |
| Auditability | 100% of production money movement is traceable by correlation ID |
| Scalability | Headroom at 2× peak; autoscaling queue depth within defined limits |
Payments and Fintech Uses
Transaction processing in regulated fintech isn’t a theoretical exercise. Every architecture choice becomes an operational constraint in production, most visibly where internal systems meet external rails.
Card-backed flows. Card-present and e-commerce payments require immediate authorization, token vault discipline, and chargeback-aware ledger posting. The TPS orchestrates PSP callbacks, 3DS journeys, and refund or reversal paths. It then feeds the reporting layer and fraud case management. Payment gateway integration services are where the rail-facing work begins. TPS orchestration governs what happens once that integration fires.
Account-to-account and RTP flows. Instant payment schemes shift pressure to continuous reconciliation. Returns, recalls, and name-check failures arrive asynchronously after confirmation. The TPS must model pending, posted, and rejected states explicitly so customer service and the ledger never contradict each other.
Cross-border payments. Cross-border transaction processing software has to cover FX exposure, sanctions, and AML at several layers. It also covers correspondent handoffs, timeouts, and settlement across time zones. One source of truth has to hold when settlement takes hours or days.
DashDevs delivery: BNPL orchestration. In our payment orchestration work for a leading BNPL provider, DashDevs centralized repayment collection. The rails were cards, wallets, tokenized payments, and bank-to-bank methods. A unified ledger tracks transaction flows across rails and currencies. The system is designed to handle up to 10,000 concurrent payment requests per second for campaign traffic.
Operational checklist for payment-heavy TPS teams.
| Area | Question your TPS must answer |
|---|---|
| Screening | What happens to funds if a hit requires manual review? |
| Returns | How do ACH or card returns unwind ledger entries and fees? |
| FX | Where is the rate locked, and how is P&L recorded? |
| Partner outage | Do you queue, fail closed, or fail open, and who approved that policy? |
Build, Buy, or Compose: TPS Architecture Decisions
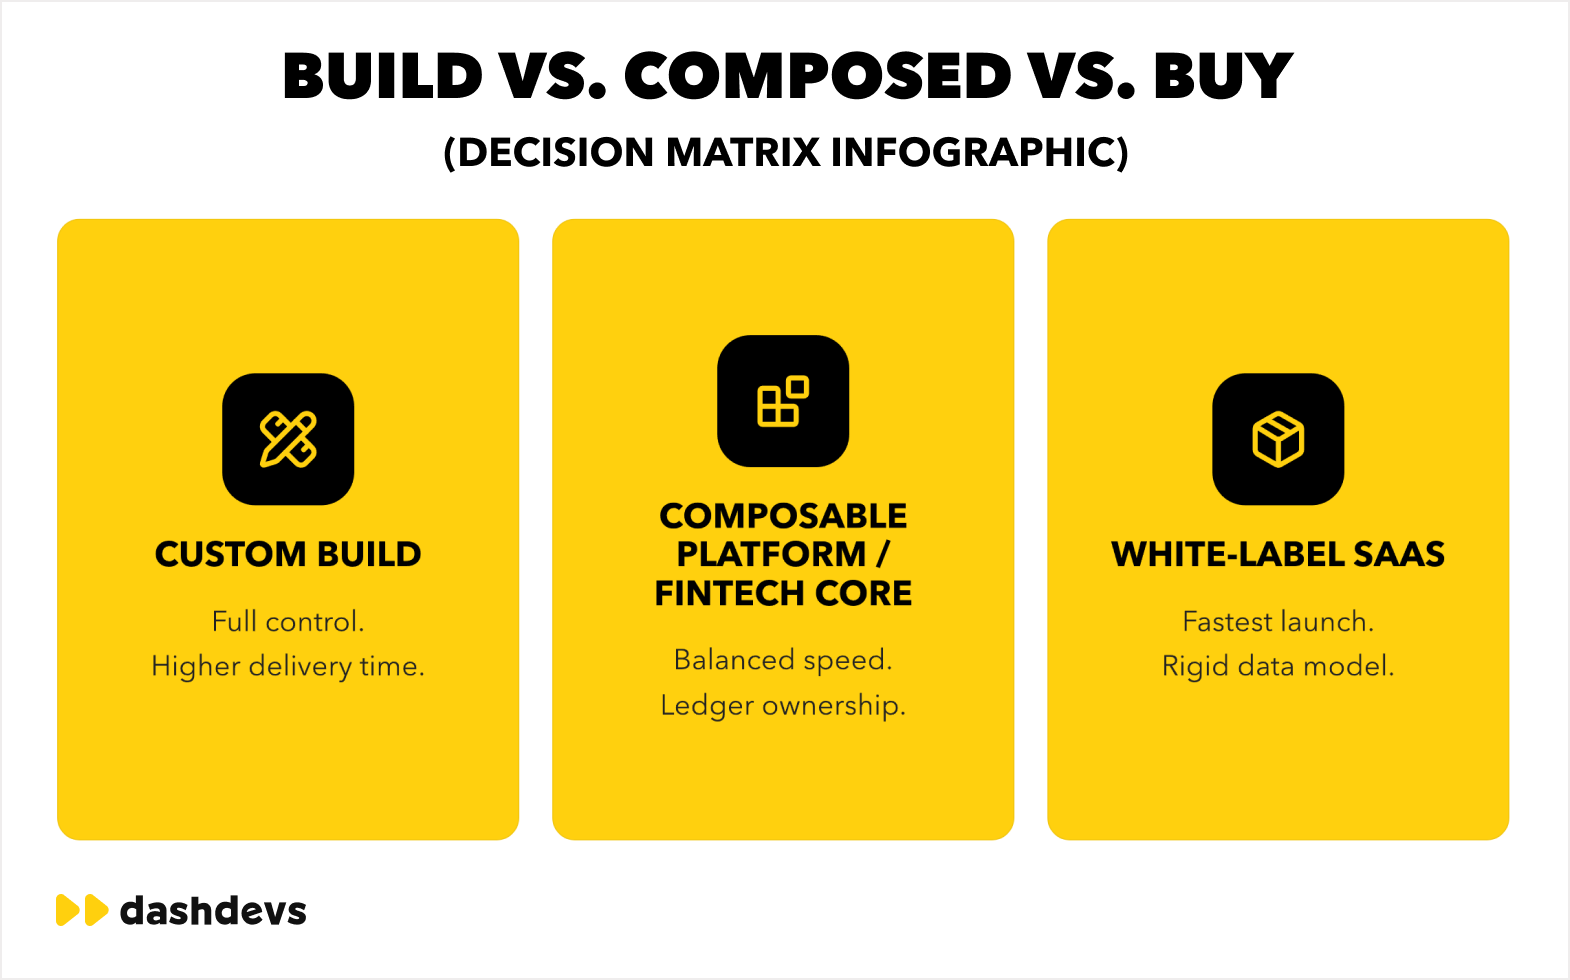
The build vs buy question for a TPS is rarely a clean binary. Most teams end up composing. They use a vendor for rail integration, build the transaction processing unit and ledger in-house, and orchestrate across both. The decision variables are transaction volume, latency, licensing, and integration scope. They also include how much of the stack the team can own in production.
Custom build gives full control over every ledger design decision, processing rule, and data model. The cost is delivery time and team size. The core model defines the ledger primitives the TPS sits on. The Nexus digital banking platform is a proprietary build with independently scalable transaction-processing components. It serves several financial product types from one architecture.
White-label SaaS platforms compress time to market but constrain ledger design. Teams that outgrow the platform’s data model face expensive migration or permanent workarounds. Vendor lock-in on the transaction processing unit is the highest-risk version of this outcome.
Composable platforms are the middle path. Teams that need production-grade processing without a 12-month custom cycle can start from a platform. Fintech Core is DashDevs’ composable fintech infrastructure and orchestration platform for launching, expanding, or modernizing regulated financial products. It gives teams a faster starting point than a custom build, with more flexibility and control than traditional white-label or SaaS platforms. Fintech Core is typically 12 weeks into production.
For high-throughput trading with strict consistency, see our matching engine for a regulated digital asset platform. It shows how composable infrastructure performs at a production scale.
Decision framework.
| Scenario | Likely best fit |
|---|---|
| Licensed EMI or fintech with confirmed volume needs a fast launch | Composable platform (Fintech Core) |
| Bank or large FI with existing core, adding a new product line | Custom build on existing ledger primitives |
| Early-stage product, pre-licensing, volume unproven | SaaS / BaaS with an exit strategy planned upfront |
| Multi-rail, multi-currency, multi-entity at scale | Custom or composable, SaaS constraints emerge fastest here |
Advantages of a transaction processing system
These advantages compound over time. Early on, a TPS looks like faster operations. At scale, it becomes the difference between trusted money movement and a brand-threatening incident.
Operational advantages.
- Fewer human touches per transaction reduce unit cost as volume grows. Automated processing does that when capacity is engineered for the peak.
- Business rules live in code and configuration, not in tribal email instructions or spreadsheet formulas.
- Global payment and currency support from a single TPS platform rather than duplicate logic per country or corridor.
- Predictable performance under load means autoscaling, queues, and back-pressure are explicit. Peak periods are a capacity plan.
Risk and compliance advantages.
| Advantage | Why it matters |
|---|---|
| Fraud containment | Centralized decisioning and velocity checks across all channels |
| Regulatory posture | Consistent KYC/AML hooks and reporting extracts; define policies once |
| Partner confidence | Issuers, schemes, and sponsor banks trust APIs that return coherent IDs and statuses |
| Customer trust | Refunds, disputes, and holds explained with data |
Where advantages disappear. Advantages vanish when shadow processing grows beside the primary TPS. Parallel spreadsheets, ad hoc scripts, or partner portals then become the system of record. At that point, the TPS is a UI. Banking software development services that span the full stack cover API, ledger, and core integration. They deliver the operational advantages in the design.
TPS is boring until it isn’t. Then it is the only system anyone cares about.
The Architecture Holds. The Complexity Is in the Production Choices.
The design isn’t a one-time architecture decision. It is an ongoing commitment to correctness, auditability, and operational control. That commitment runs across every rail, ledger, and compliance layer the product touches.
Teams that treat TPS design as an early priority have an easier path. That shows up in licensing audits, partner integrations, and scale. Teams that treat it as plumbing discover the gaps at the worst moment. That moment is under volume, during an audit, or when a double charge reaches a customer.
For teams at the decision point, DashDevs brings production delivery across the full TPS stack. That runs from custom ledger architecture to composable platform deployment. Our fintech architecture guide covers modular design, tech debt, and scalability across product types. It helps teams set trade-offs before they commit to a build.
Reach out to explore how your TPS design maps to your transaction volume, licensing obligations, and growth stage.
Market Context: Transaction Processing Volume in 2026
In March 2026, EUR instant payments in TIPS averaged 4.5 million a day, the European Central Bank reported.
That volume is why policy, monitoring, and proof sit on the production path. A nightly file can’t be the only status a customer sees.
Always-on capacity, continuous reconciliation, and a fast authorization path follow from that. Payment product strategy has to live with that load.
What to lock before the next rail
The customer decision, the ledger line, and the scheme file have to tell the same story.
Commit the answer while the customer waits. Let clearing land on the rail’s own window. Keep pending, posted, and rejected as separate states.
Own the idempotency key, the unwind, and the evidence. Rent the scheme file when it is a commodity. Use a composable platform when the ledger still has to stay yours.
Share article
